【Wdoodoo Weekly Paper Industry Report】Bottom grinding of pulp prices waiting for inventory clearance, focusing on long-term stabilization opportunities under low valuation
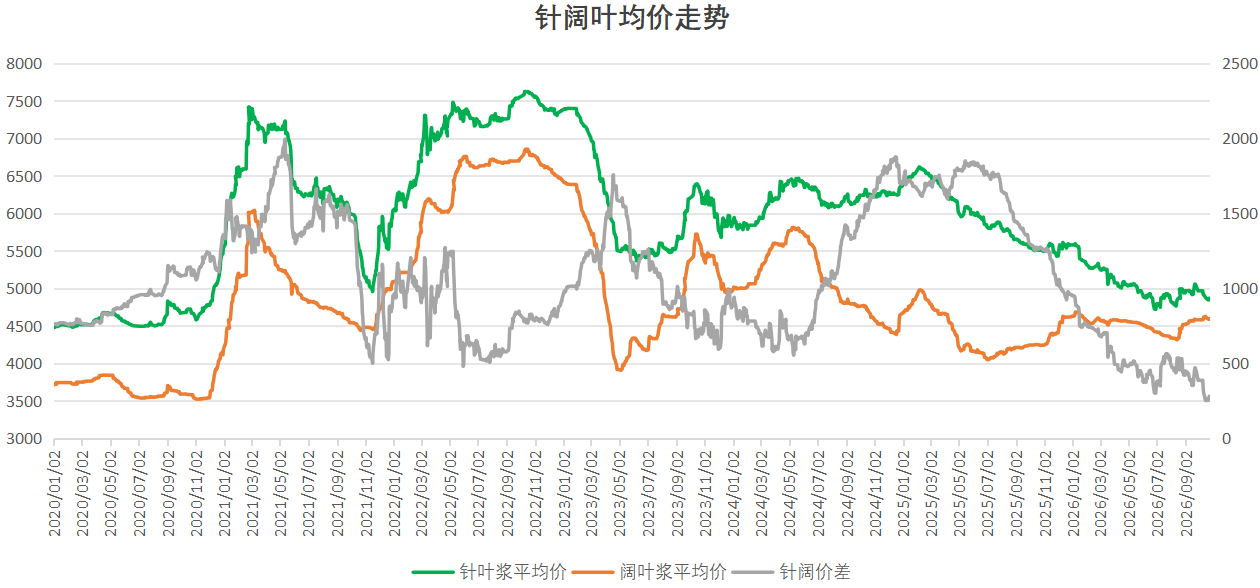
Affected by the macro atmosphere, pulp was weak and fluctuated last week. The average spot price of needle pulp is around 4867 yuan/ton, an increase of 3 yuan/ton compared to the previous period; The average spot price of broad-leaved pulp is 4587/ton, a decrease of 15 yuan/ton compared to the previous period. Traders are reluctant to sell at high prices, and the spot basis has generally turned positive. However, the production and sales of finished paper are weak, paper mills are cautious in replenishing raw materials, and pulp inventory is slowly being depleted.
1. High crude oil prices and increased expectations of macroeconomic recession.
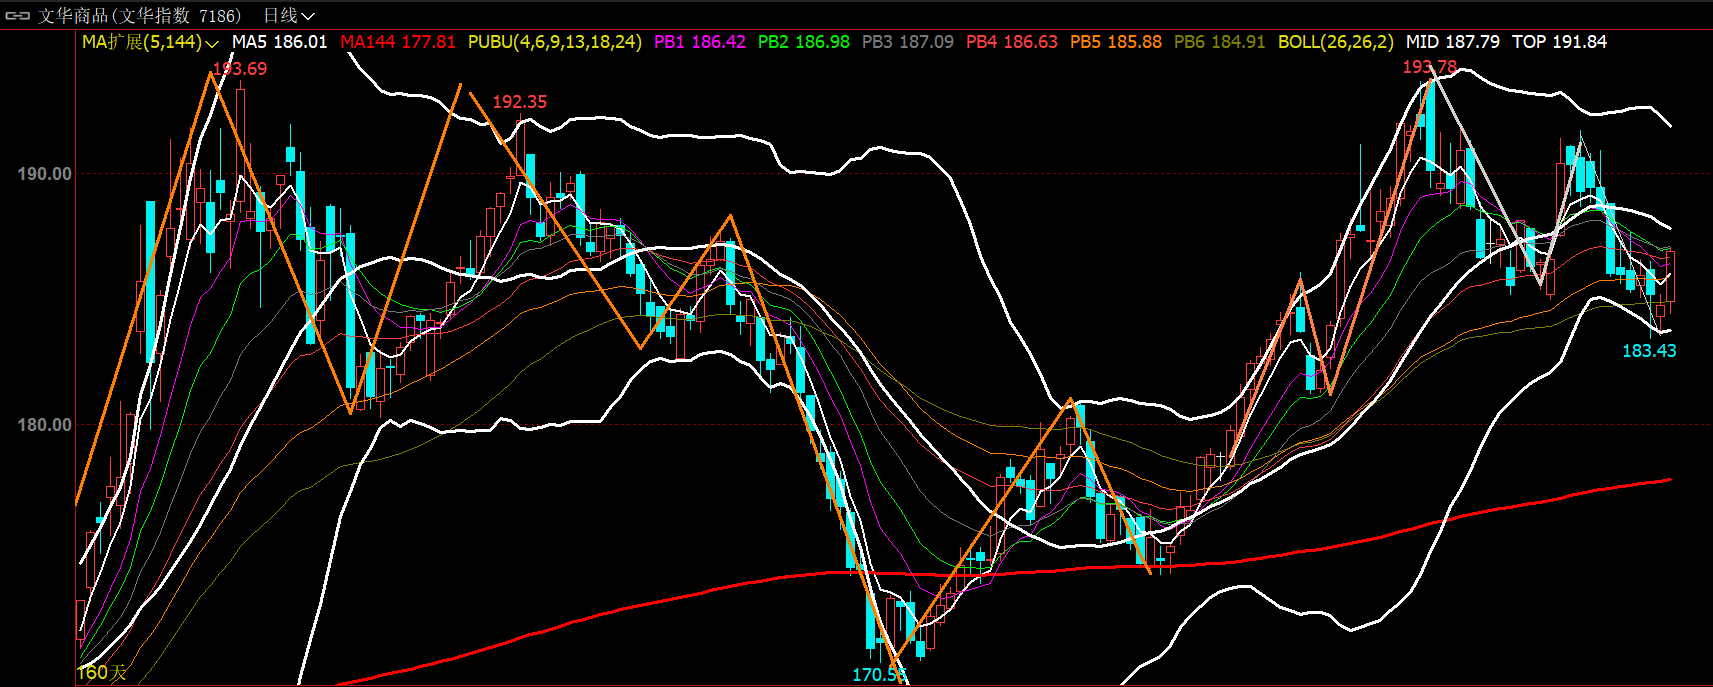
Recently, the fluctuating public opinion in the Middle East and the rising geopolitical risks have led to sustained high energy and chemical costs, severely suppressing downstream demand expectations. The tight liquidity of the US dollar in the global market and the expectation of recession are once again suppressing the trend of commodities. This week, there have been intense macroeconomic events, with a focus on the impact of the "15th Five Year Plan" policy adjustments at the Fifth Plenary Session, the Federal Reserve's interest rate hike resolution, and the Middle East energy and chemical transmission on the market.
2. Production capacity expectations have risen again, and the impact of old warehouse receipts still needs to be resolved.
Belarus plans to build an 800000 ton pulp mill, APP plans to add 2 million tons of pulp production capacity in Guangxi and Hainan, and Canada's Needle Leaf Pulp Good Voice plans to resume production in November. The expected increase in long-term production capacity has suppressed last week's market trend.
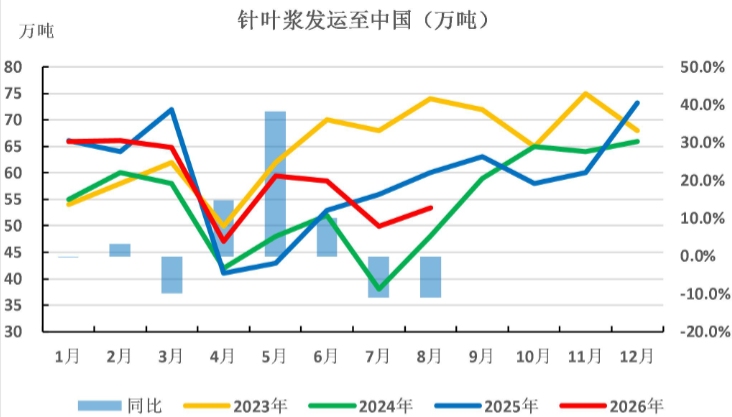
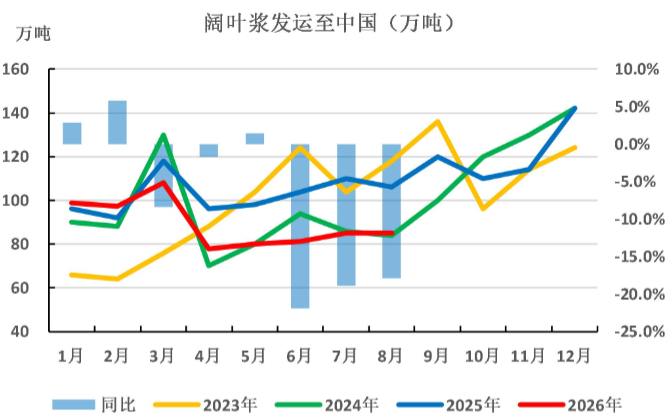
However, due to the impact of price decline, the production of coniferous and broad-leaved wood has continued to decrease this year. PPPC data shows that global coniferous and broad-leaved wood shipments in August were at a low level in recent years, and pulp shipments to China have decreased year-on-year. With the recent drop in the market to needle cash costs, paper mills have been active at low point prices, and spot spreads have generally turned positive. Attention should be paid to the digestion of old warehouse receipts and port needle prices.
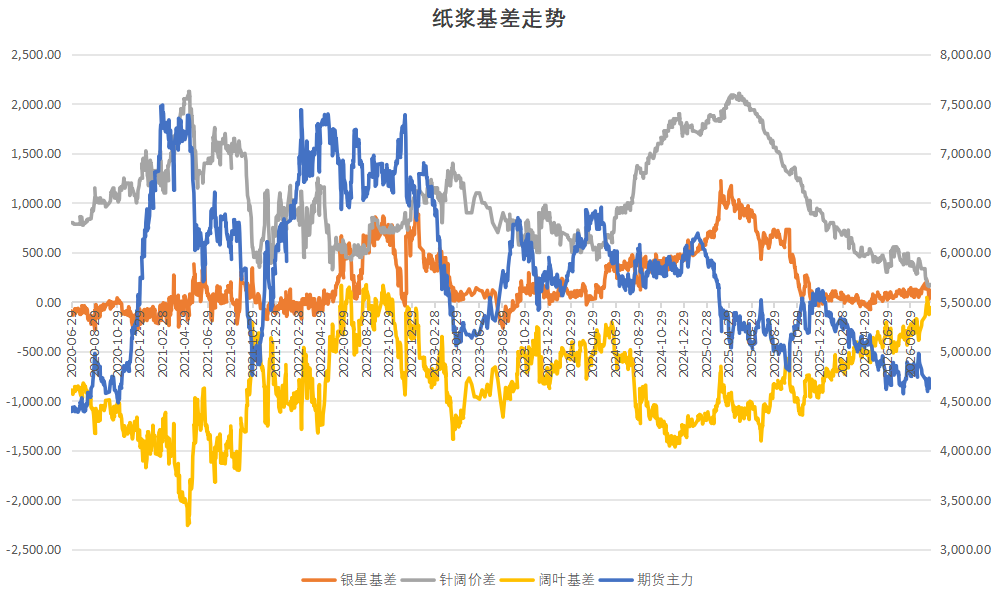
The inventory of broad-leaved ports is still at a low level, and the overall trend is relatively stable. However, the current historical low level of the price difference between the needle and the broad leaf market is dragging down the performance of the broad leaf market due to the weakening of the market
3. Downstream demand is expected to weaken
Paper making is expected to be less prosperous during the peak season and less prosperous during the off-season. The production and sales of various mainstream paper types have further weakened, and the price of finished paper continues to decline. The pressure of white cards and cultural paper is relatively high, and only life paper remains stable. Downstream raw paper enterprises are generally experiencing losses in processing, with paper mills mainly reducing prices and increasing production volume, resulting in low gross profit. It is expected that the operating rate will be difficult to increase in the near future, and the demand side's support for pulp is average. Pay attention to the inventory turnover of finished paper products.
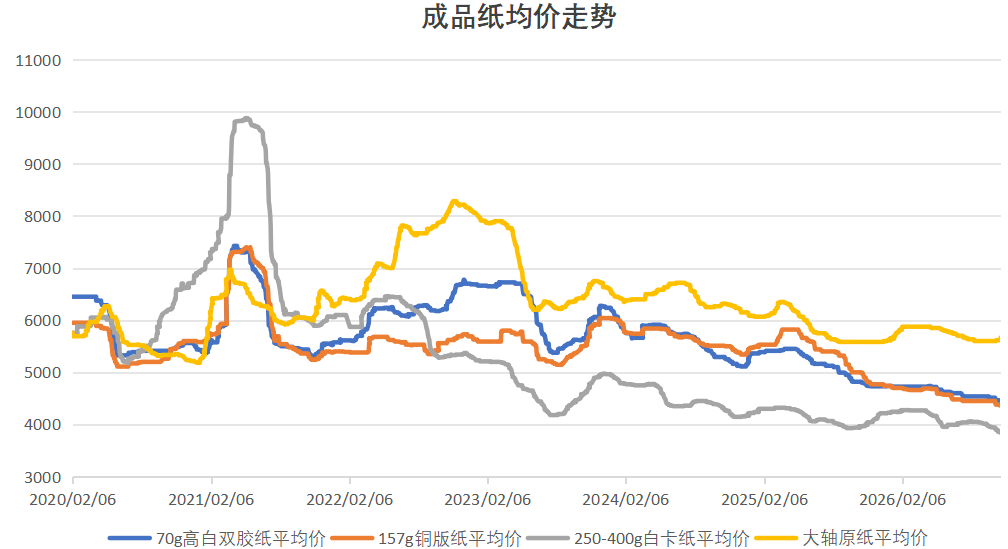
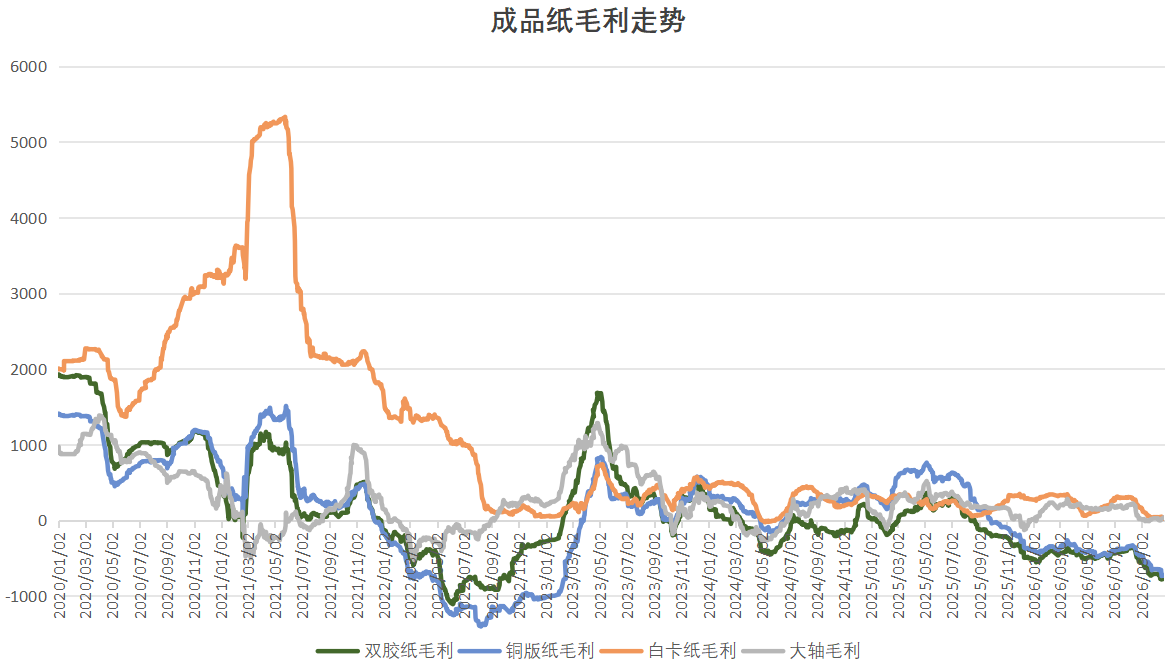
Overall, the production and sales of finished paper are weak, the willingness to replenish raw materials is not good, and the clearance of pulp port inventory is slow. However, external pulp mills have stopped reducing production to boost prices, and the needle base has generally turned positive, with a low needle wide price difference. As the supply margin of needle pulp shrinks, the advantage of low valuation becomes increasingly apparent. The upward and downward driving force of pulp is limited, and it is expected that the main core fluctuation range will still be between 4600-4900. We will pay attention to the digestion of finished paper and needle inventory in the future, and observe the short-term situation. How many months can we try to stabilize the market.
-
【Wdoodoo Weekly Paper Industry Report】Bottom grinding of pulp prices waiting for inventory clearance, focusing on long-term stabilization opportunities under low valuation7141
-
【Wdoodoo Weekly Cotton Report】Supply and demand lack strong drivers, with Zhengzhou cotton prices fluctuating weakly8133
-
【Wdoodoo Weekly Paper Industry Report】Pay attention to the situation of needle leaf destocking under low valuation6207
-
【Wdoodoo Weekly Cotton Report】Production cuts are limited, Zhengzhou cotton rebounds weakly6710
-
【Wdoodoo Weekly Paper Industry Report】Raw paper processing is under pressure, and the pulp trend is loose9874