【Wdoodoo Weekly Cotton Report】Production cuts are limited, Zhengzhou cotton rebounds weakly
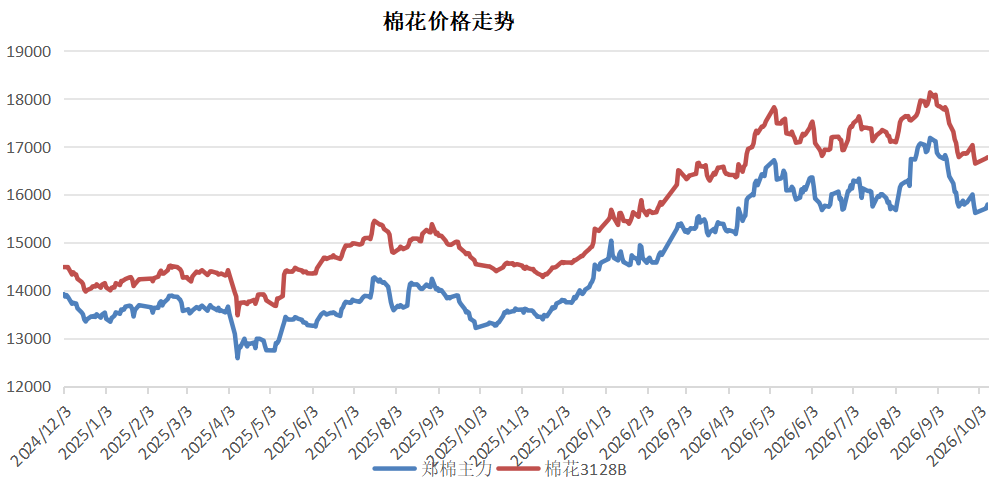
This week, Zhengzhou cotton futures surged and then retreated. CF01 closed at 15,850 yuan/ton, up 60 yuan/ton from the previous session; national cotton 3128B closed at 16,870 yuan/ton, rebounding 95 yuan/ton. Expectations of reduced production in Xinjiang strengthened cost support, but high carryover inventory of aged cotton and weak demand during peak season offset the positive impact.
1、 Macro performance is neutral.
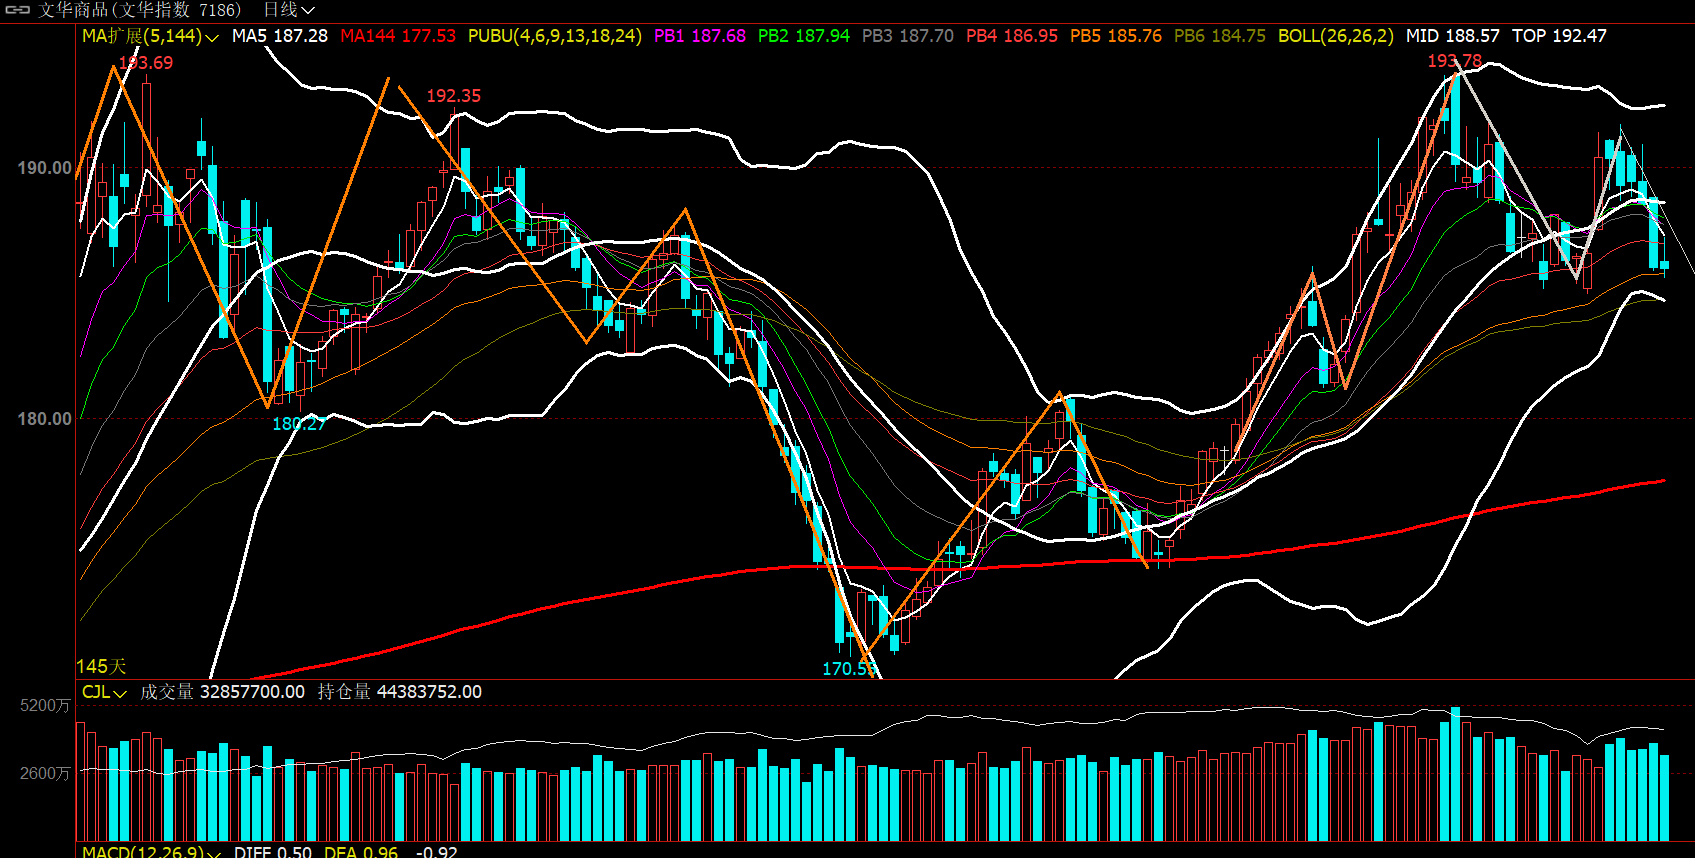
September US inflation data exceeded expectations and rose, with expectations of a rate hike in October heating up. Mid week pressure on commodities. However, as the United States enters the sprint stage of the midterm elections, the Trump administration has a strong demand for improving the liquidity environment. Federal Reserve officials tend to be hawkish in their words and dovish in their actions, with most leaning towards raising interest rates once at the end of the year. The probability of the weekend market remaining unchanged in October is 83.9%, with a 25bp interest rate hike of only 16.1%. The downward pressure on bulk commodities has eased.
1.Supply side slightly biased towards support
The harvesting in northern Xinjiang is nearing completion, while southern Xinjiang is climbing the slopes. With the implementation of harvesting in northern Xinjiang, the weak yield and clothing percentage data have been further confirmed, and the reduction in production has exceeded the expected level in September. The market believes that the cotton production in Xinjiang has been reduced to below 7 million tons, and some institutions have lowered it to 6.8 million tons or lower.
This year, the net clothing percentage of seed cotton has decreased by 1 percentage point year-on-year, with mainstream net clothing percentage ranging from 34% to 36%. Cotton farmers are reluctant to sell due to price hikes.
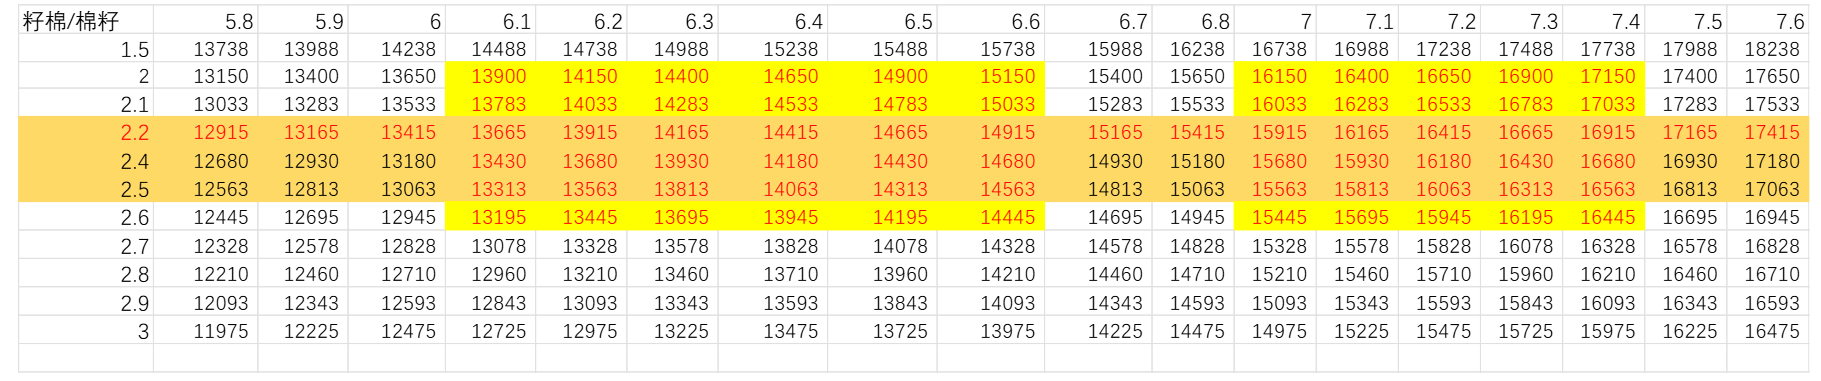
The purchase price of seed cotton in 2026/27 is mostly around 7.3-7.6 yuan/kg, and the theoretical cost of new cotton is mostly in the range of 16400-17200 yuan. It is expected that the hedging pressure will be in the range of 15900-16500 yuan.
The overall trading of cotton spot is sluggish, with textile enterprises mainly focusing on essential purchases. The market is gradually adding low-quality and low basis cotton, and the cotton spot sales basis is stable but slightly weak.
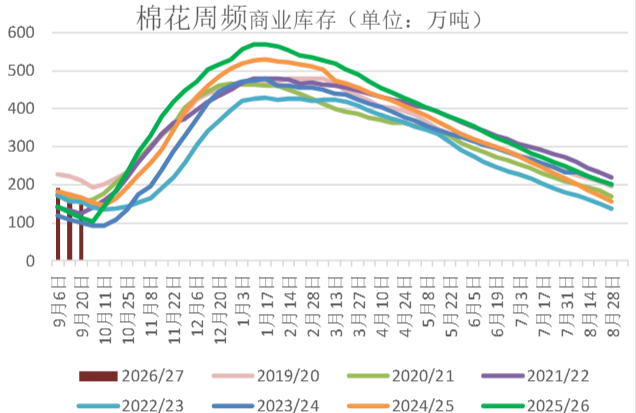
However, at the end of September, the national commercial inventory was 1.8 million tons, an increase of 634000 tons year-on-year. With the centralized public inspection and listing of new cotton, there is a seasonal increase in supply. In addition, the USDA report for the month was bearish, with increased production in the United States and Brazil offsetting to some extent the expected reduction in cotton production in Xinjiang.
2. Downstream demand is relatively weak.
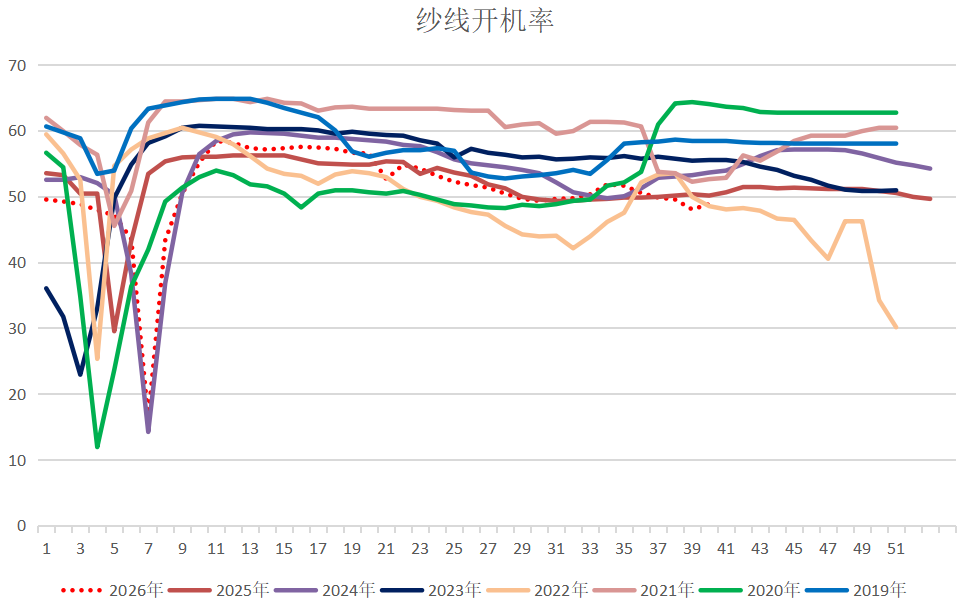
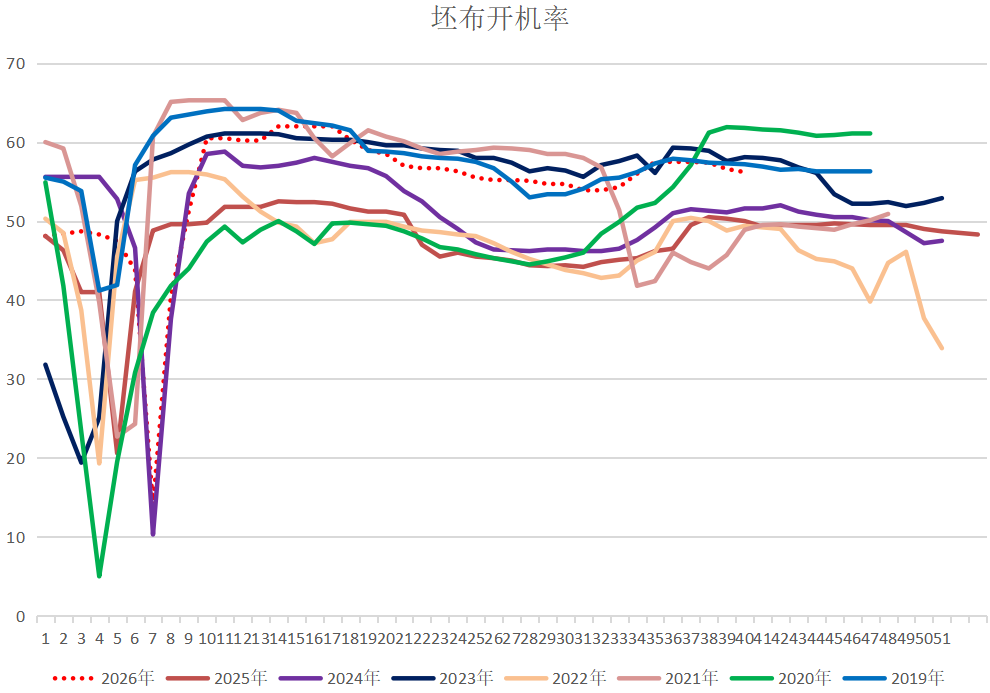
The Golden September and Silver October are coming to an end, and the demand feedback is not as expected. The current yarn production is fluctuating at a low level, with less than half of it running. The profit of the yarn factory is weak, the inventory of finished products has accumulated, and the inventory of cotton yarn at the port has risen rapidly. After the end of the peak season, it will turn into a low season, and the negative feedback of weak reality on the demand side may continue. Attention should be paid to the issues of pre demand and post risk caused by the rush to export in the first half of the year.
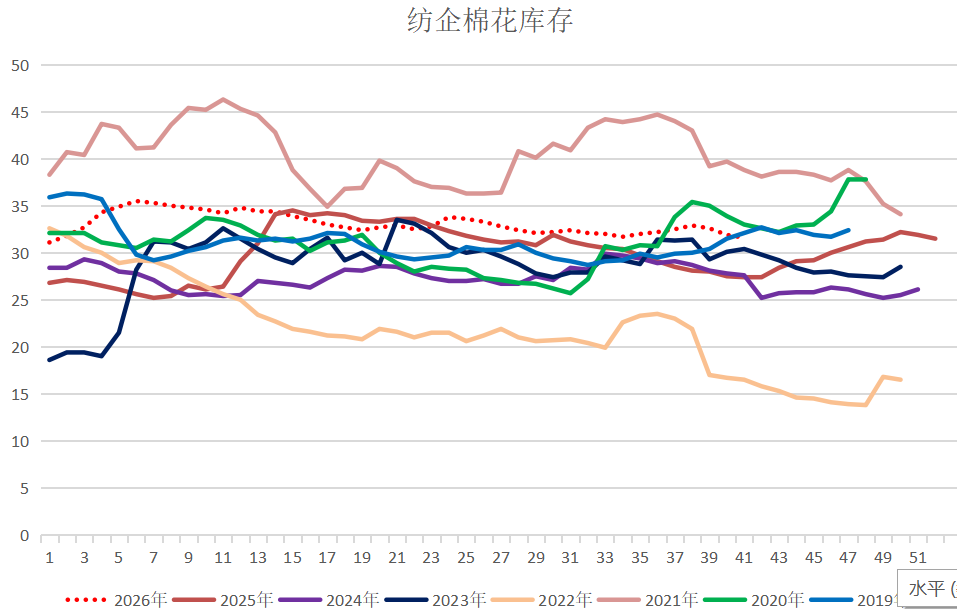
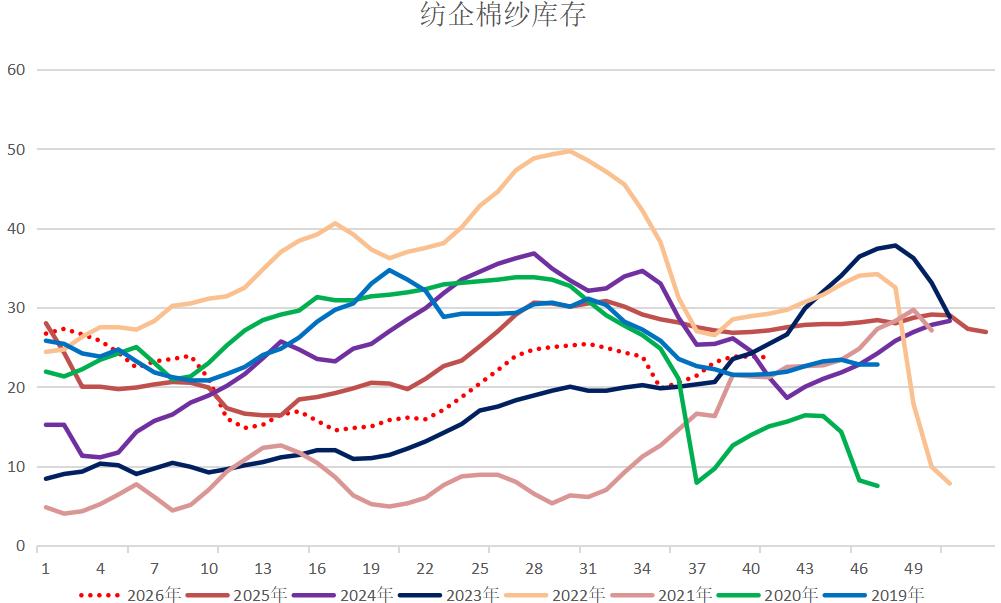
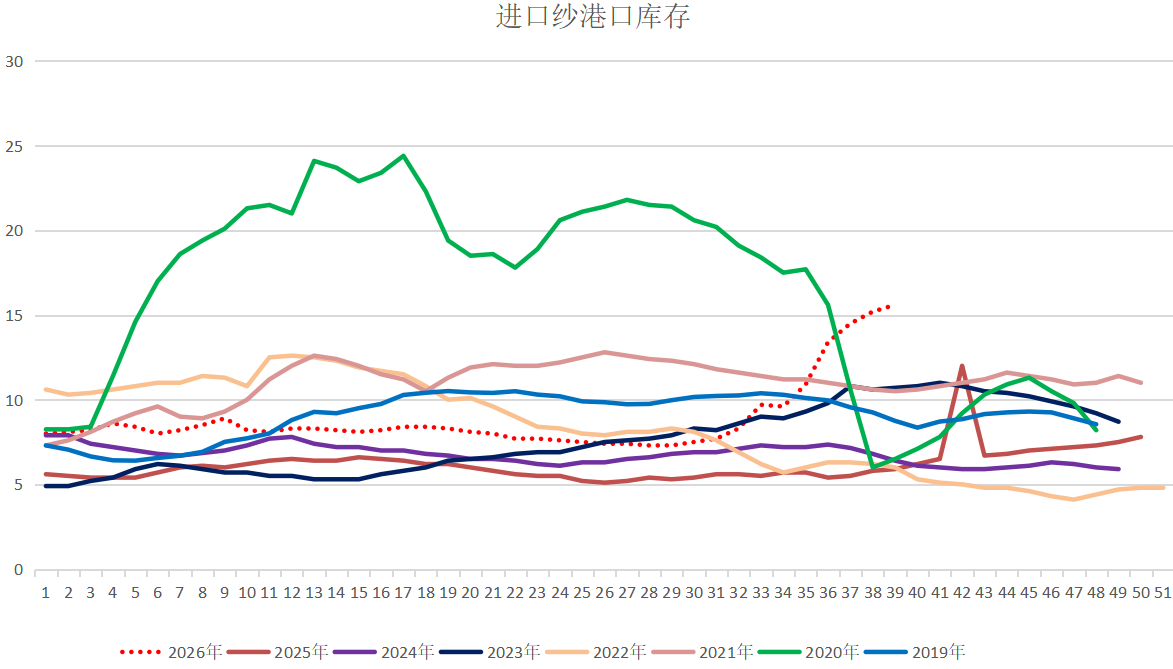
Overall, the expected reduction in cotton production in Xinjiang has increased, and the strong cost of purchasing seed cotton has supported cotton prices. However, the inventory carried over from the previous year was relatively high, and the USDA's global cotton production adjustment dispelled the positive news of Xinjiang's production reduction. The rebound of Zhengzhou cotton is constrained by weak demand and hedging pressure, and currently does not have the conditions for significant unilateral fluctuations. It is expected to fluctuate in the short-term range of 15500-16200.
-
【Wdoodoo Weekly Paper Industry Report】Pay attention to the situation of needle leaf destocking under low valuation6135
-
【Wdoodoo Weekly Cotton Report】Production cuts are limited, Zhengzhou cotton rebounds weakly6633
-
【Wdoodoo Weekly Paper Industry Report】Raw paper processing is under pressure, and the pulp trend is loose9838
-
【Wdoodoo Weekly Cotton Report】New cotton arrivals support prices, while weak demand hampers rebound7552
-
【Wdoodoo Weekly Paper Industry Report】Port destocking slows down, pulp surges fail6483