【Wdoodoo Weekly Cotton Report】Macroeconomic weakness and weak demand continue to drive Zhengzhou cotton prices lower
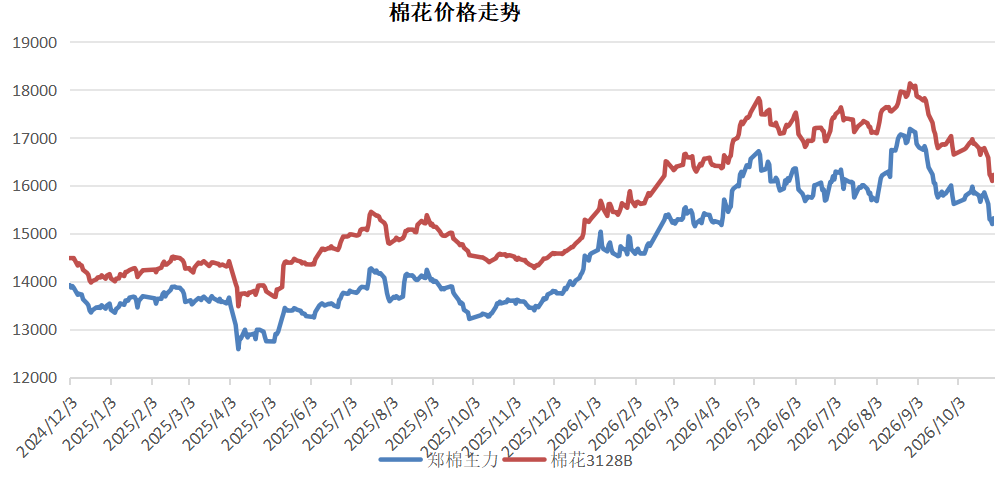
Last week, Zhengzhou cotton broke through and fell. CF01 closed at 15315 yuan/ton, down 540 yuan/ton month on month; National cotton 3128B closed at 16220 yuan/ton, a month on month decrease of 560 yuan/ton. The macro atmosphere is bearish, downstream demand is sluggish, and the accumulation of hedging and selling by cotton mills continues to suppress the market.
1、 Macro recession atmosphere deepens, AI's fulfillment falls short of expectations
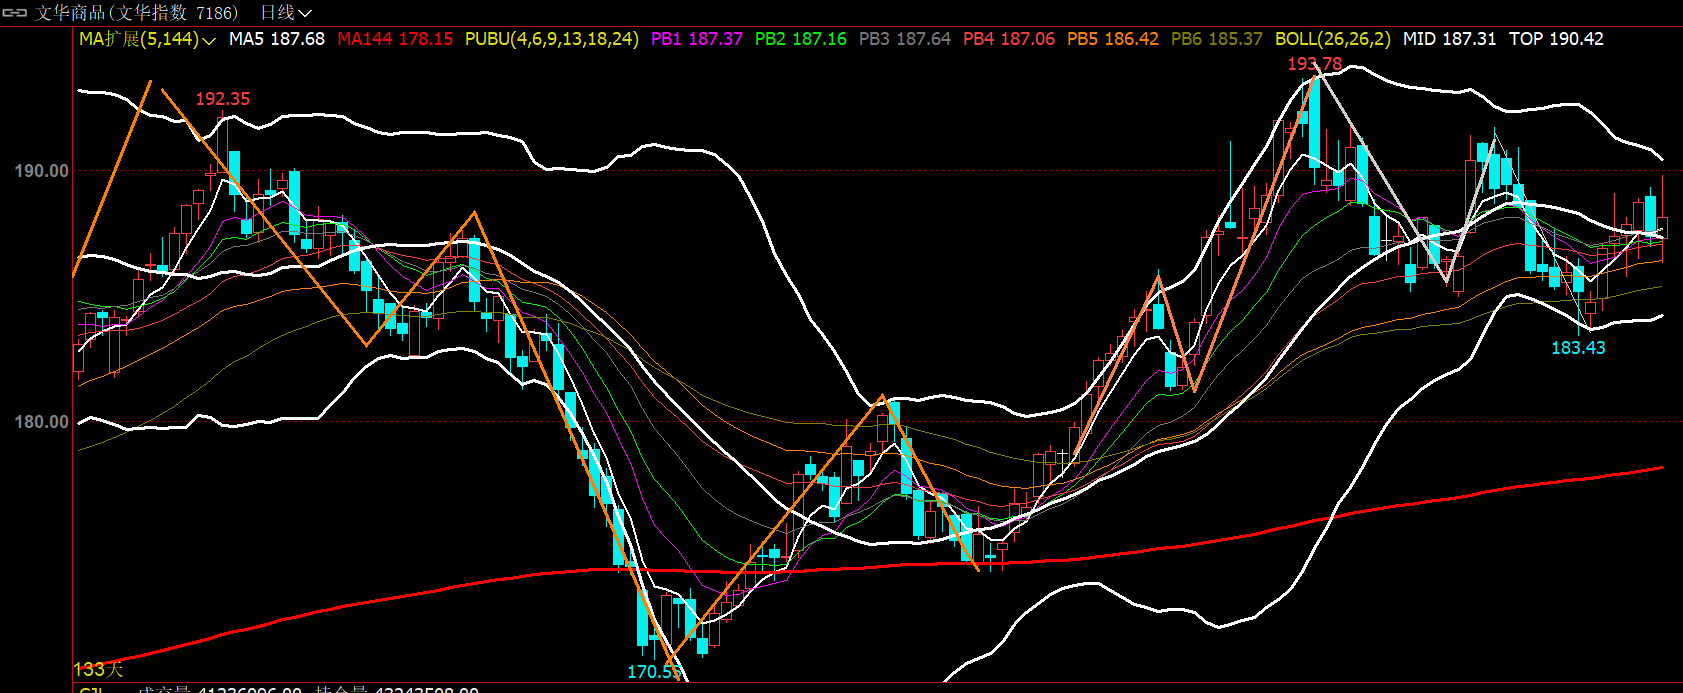
The intensification of geopolitical conflicts in the Middle East has led to sustained high costs of inflation expectations, tightening US dollar liquidity and suppressing commodity demand. AI returns fell short of expectations, raising doubts about capital expenditures and increasing expectations of a macro recession.
2、 The supply side is biased towards neutrality.
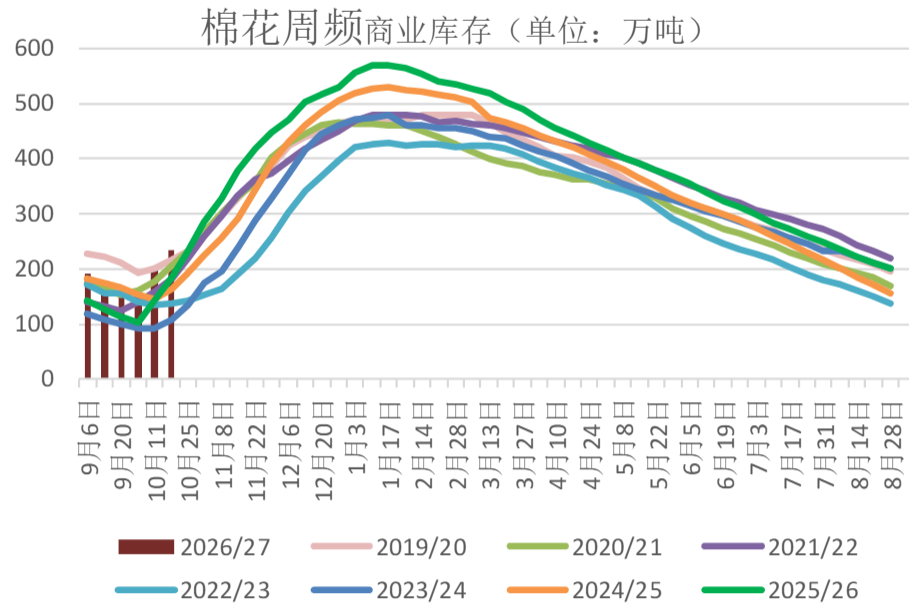
The harvest of new cotton is coming to an end, with a total of 1.83 million tons of new cotton inspected nationwide as of October 29th, an increase of 24% year-on-year. The disagreement over production cuts in the new year was quickly resolved by the accumulation of commercial inventory. As of October 15th, the national commercial cotton inventory with BCO caliber was 2.6118 million tons, an increase of 846300 tons from the end of September and a year-on-year increase of 891600 tons; Among them, the inventory in Xinjiang was 1.5701 million tons, an increase of 880700 tons from the end of September and a year-on-year increase of 406300 tons.
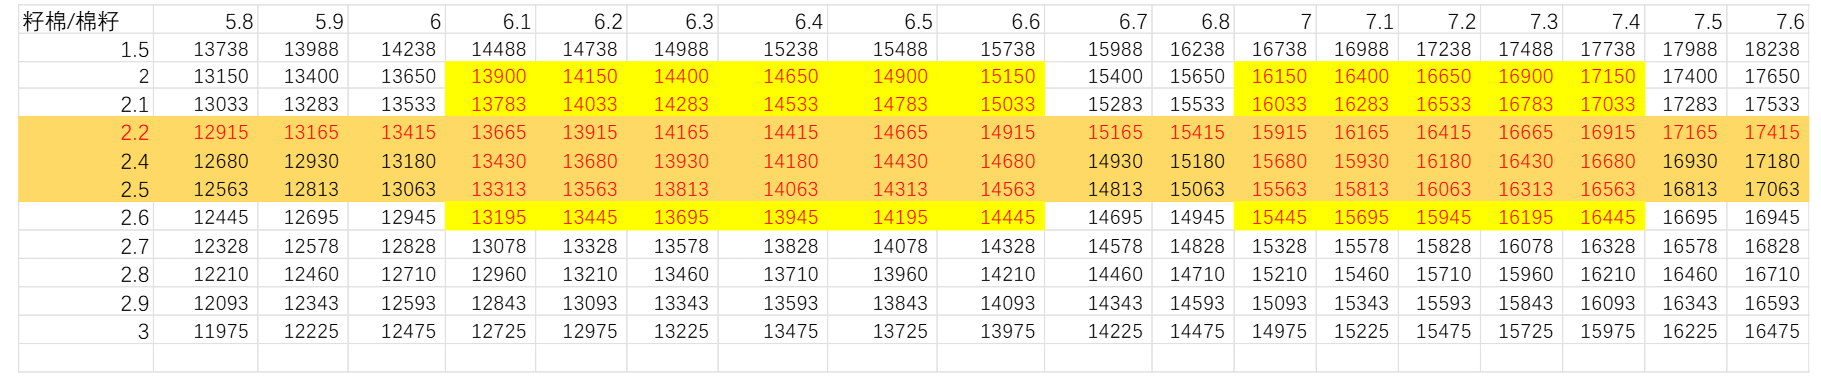
The theoretical cost of new cotton is mostly in the range of 16400-17200, and the main force 01 has accumulated a lot of hedging pressure around 16000 in the past month.
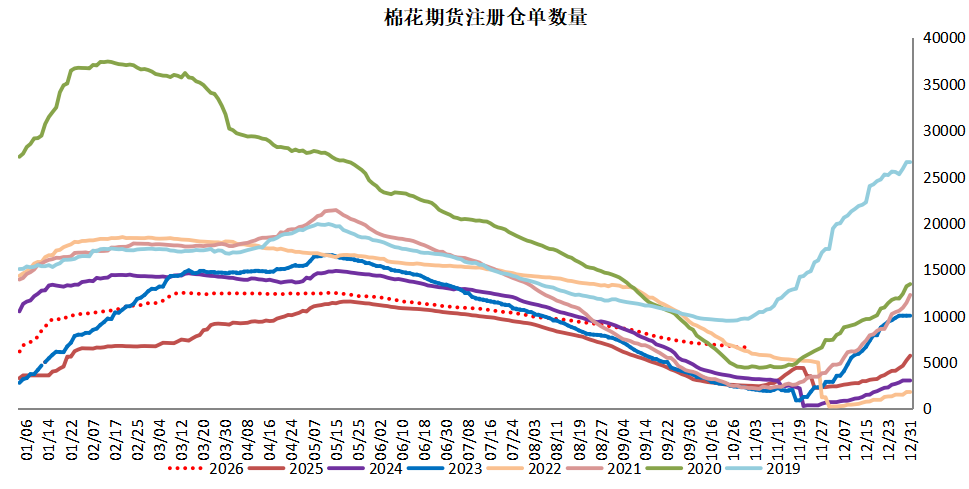
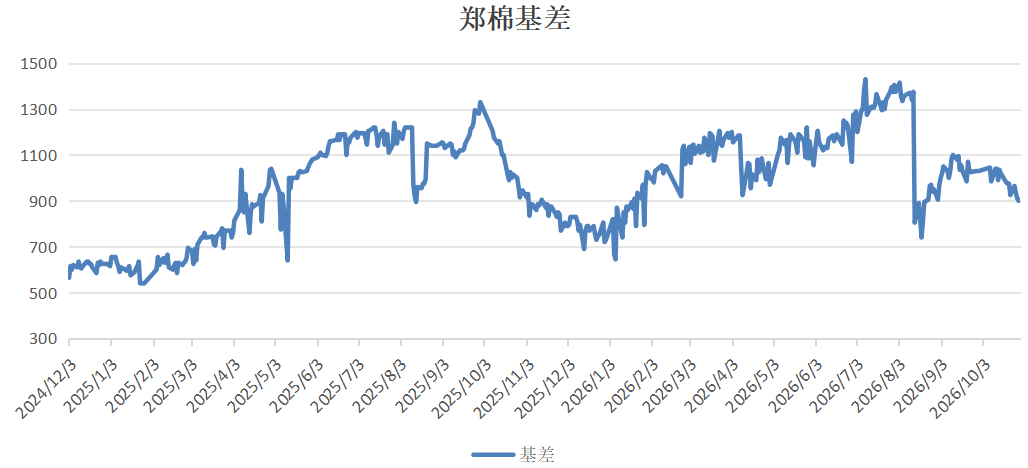
It is worth noting that after the reform of the premium for delivery in the new year, the premium for delivery warehouses in mainland China has generally been reduced by 200 yuan/ton, and the premium for high-quality indicators has also narrowed, resulting in a decrease in the cost-effectiveness of warehouse receipt registration. Combined with the average quality of cotton this year, it is expected that the number of warehouse receipts will be limited, which may be favorable for future delivery market or 1-5 price difference.
3、 Downstream demand is weak.
The peak season is coming to an end, and there is insufficient effective demand in the market. The current production of yarn and embryo fabric is fluctuating at a low level, while cotton yarn transactions are light. Yarn continues to accumulate inventory, especially with the rapid rise of cotton yarn inventory in ports. The procurement of raw materials by enterprises is mainly based on on-demand purchase and replenishment of essential inventory, and the willingness to proactively replenish inventory is low. Before the effective disposal of yarn inventory, it is difficult for cotton prices to rise.
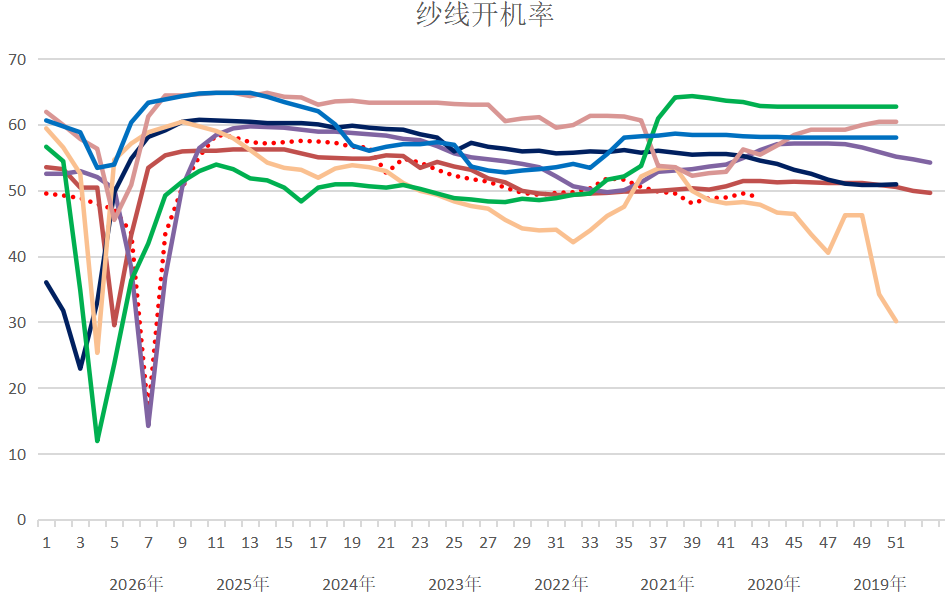
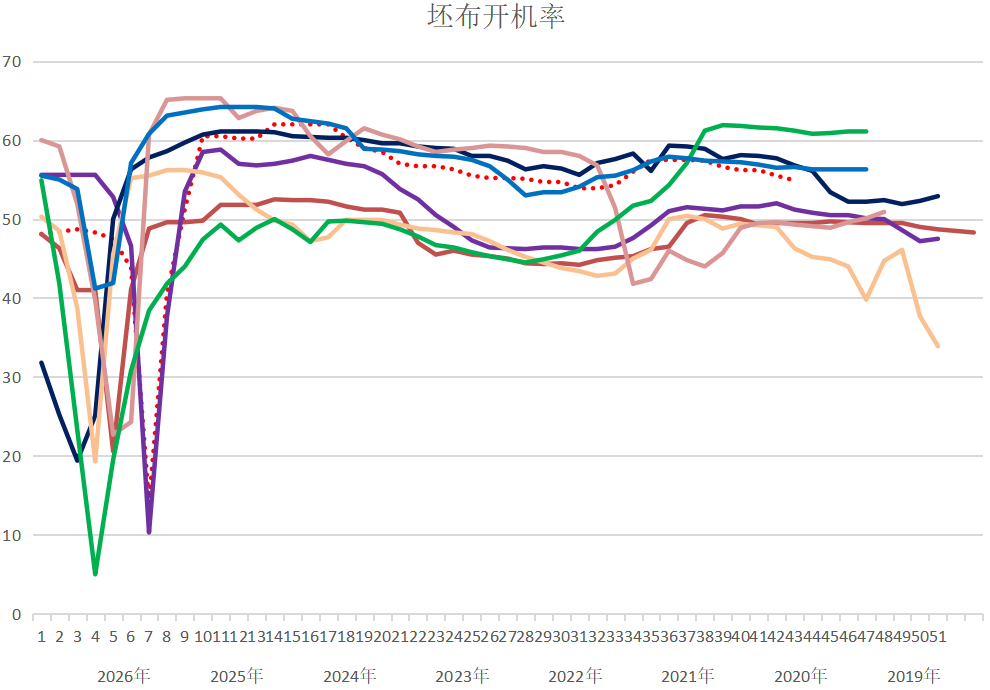
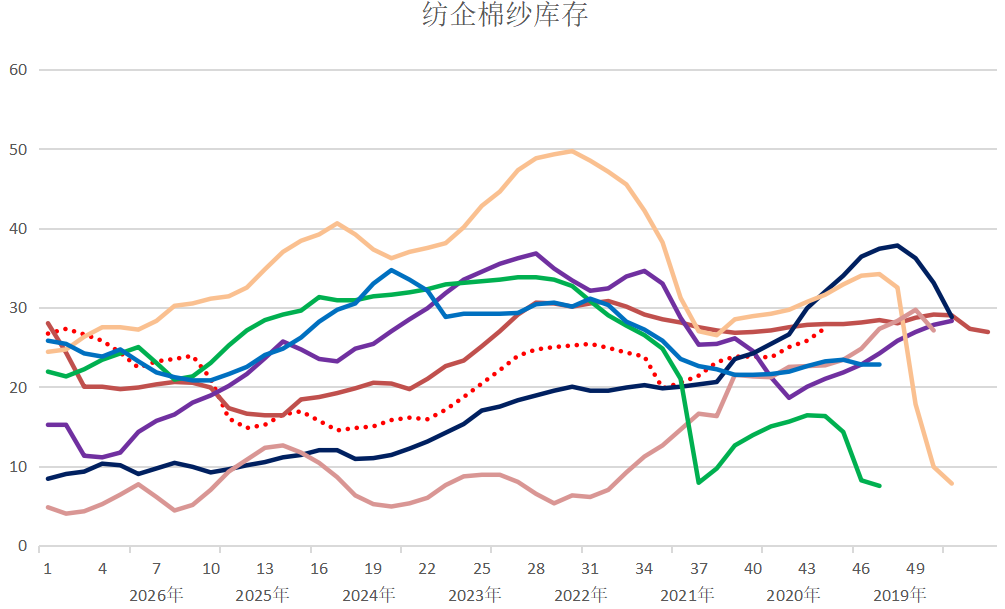
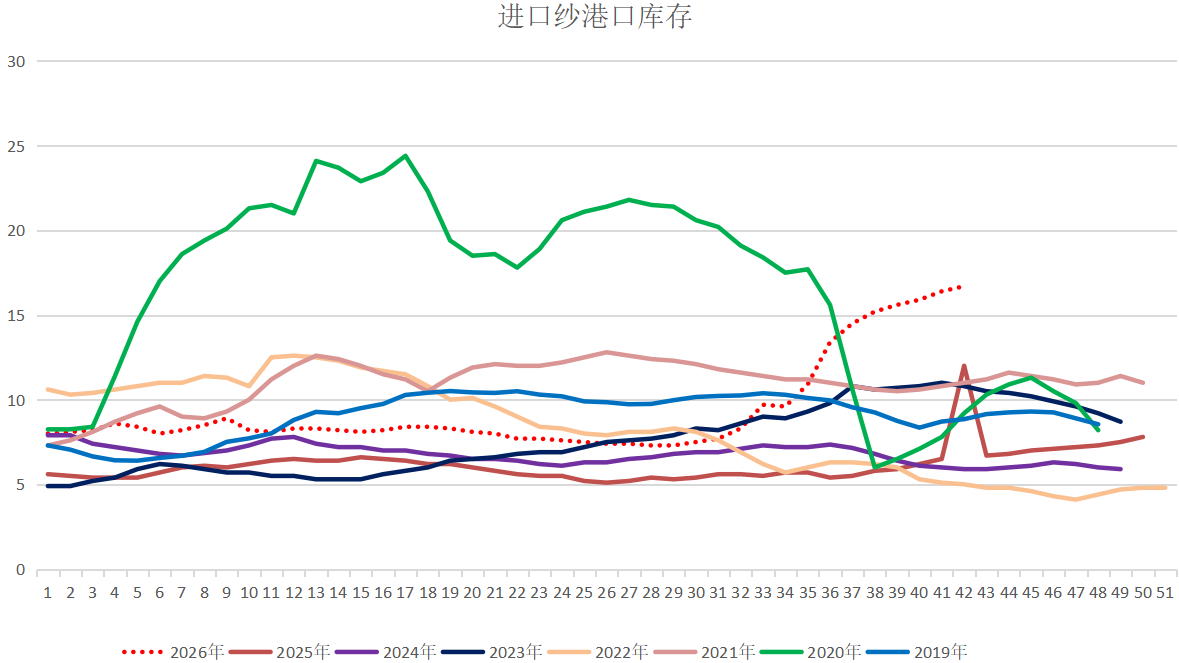
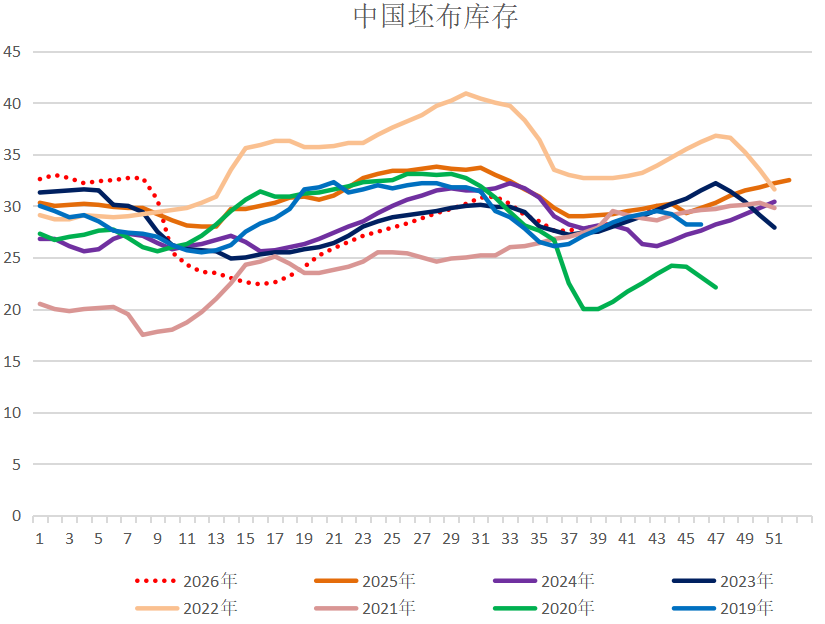
Overall, the macro atmosphere is bearish, textile demand is weakening, cotton and cotton yarn inventories are rapidly accumulating, and the trend of Zhengzhou cotton below 15500 is bearish. However, the expected warehouse receipts are relatively low, and the cost of seed cotton has increased. After digesting the yarn inventory, there is still an opportunity for upward growth in the medium and long term.
-
【Wdoodoo Weekly Paper Industry Report】Spot basis strengthens, pulp oversold rebounds5228
-
【Wdoodoo Weekly Cotton Report】Macroeconomic weakness and weak demand continue to drive Zhengzhou cotton prices lower9806
-
【Wdoodoo Weekly Paper Industry Report】Bottom grinding of pulp prices waiting for inventory clearance, focusing on long-term stabilization opportunities under low valuation7197
-
【Wdoodoo Weekly Cotton Report】Supply and demand lack strong drivers, with Zhengzhou cotton prices fluctuating weakly8174
-
【Wdoodoo Weekly Paper Industry Report】Pay attention to the situation of needle leaf destocking under low valuation6248