【Wdoodoo Weekly Paper Industry Report】The pulp warehouse receipt has been out of stock for a long time, and the packaging paper mill has raised prices in a centralized manner
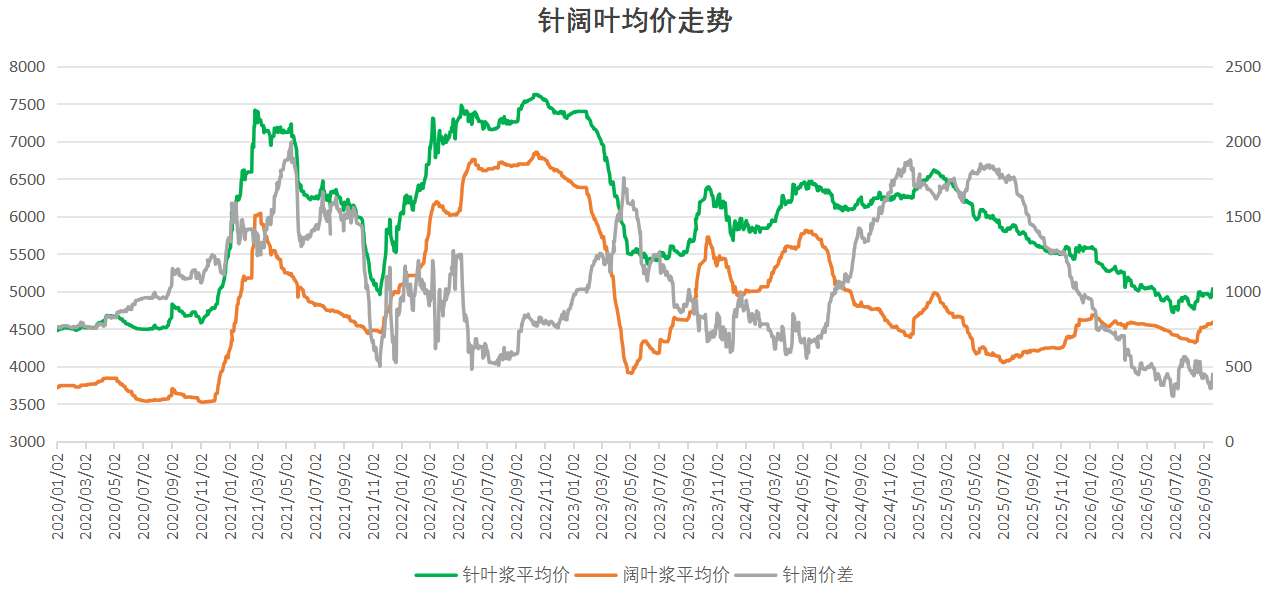
This week, the pulp first suppressed and then rose. The average price of needle pulp is around 5032 yuan/ton, with a month on month increase of 123 yuan/ton; The average price of broad-leaved pulp is 4588/ton, an increase of 24 yuan/ton compared to the previous period. The supply of broad-leaved pulp for external sale is relatively tight, and the significant destocking at ports is supporting the rebound of the coniferous period. However, the peak season for finished paper is not prosperous, and paper mills are mainly destocking, with caution in chasing higher raw materials.
1. Macro bearish release
At the macro level, the overall sentiment is bearish, with the Federal Reserve raising interest rates by 25 basis points as scheduled, and expectations of global liquidity tightening heating up, suppressing overall sentiment in commodities. The performance of domestic social zero data fell short of expectations, and the boost to terminal consumption was insufficient. However, short-term macro negative factors have concentrated and landed, and the recent intensive consultations between China and the United States to reduce risks have limited short-term macro impacts.
2. The supply pressure is still high, but there is a marginal improvement
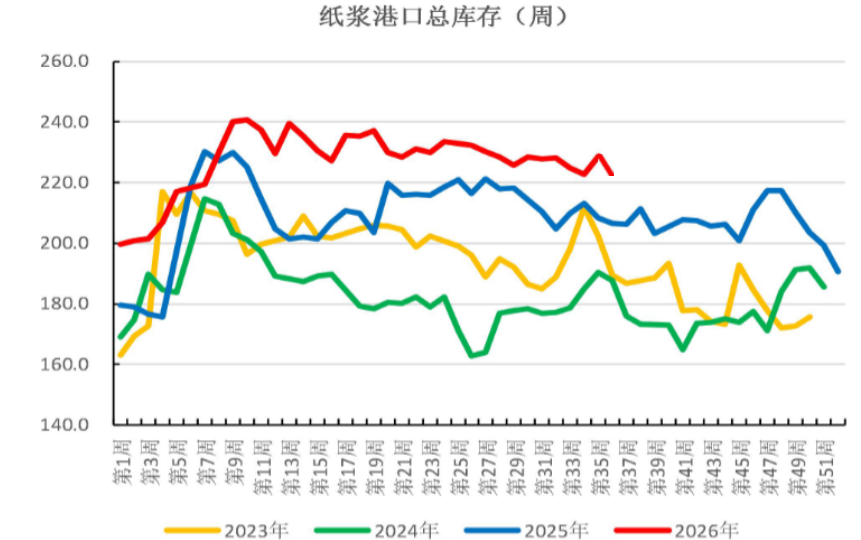
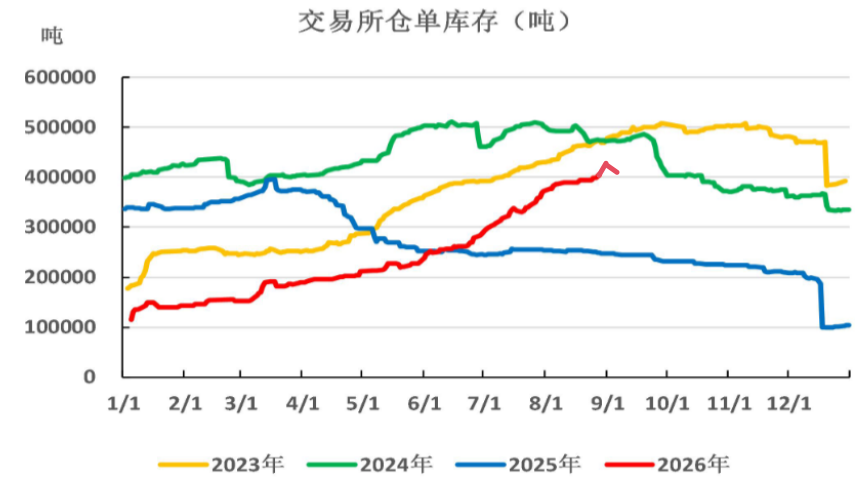
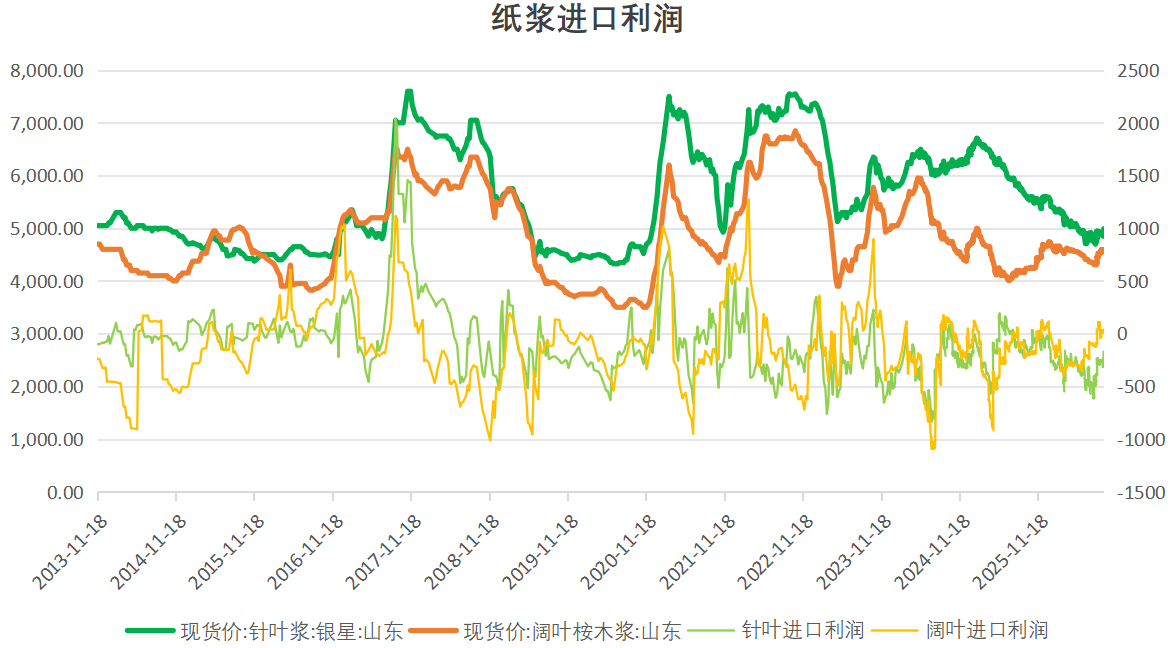
The main business of global needle pulp factories has generally entered a state of loss, with needle production capacity reduced by nearly 1.5 million tons since 2026, and there is an expectation of a contraction in long-term supply. The slow digestion of needle pulp port inventory and warehouse receipts has constrained market performance. However, this week's port inventory decreased by 100000 tons and warehouse receipts decreased by 10000 tons, slightly supporting market performance. Pay attention to the performance of warehouse receipts this week, which rose to reach the Silver Star risk-free import hedging window on Friday evening.
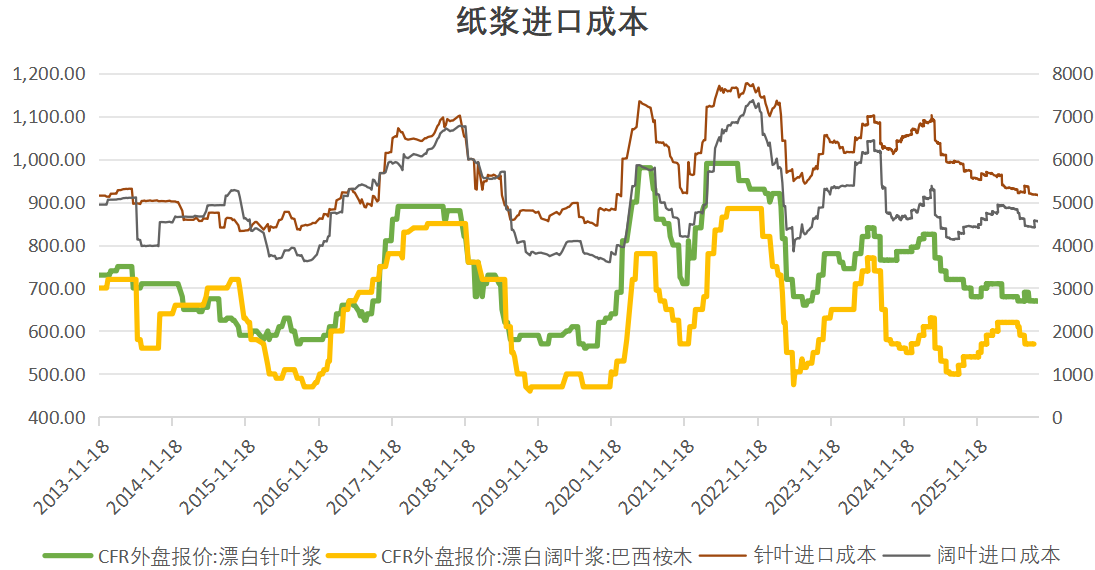
In terms of broad-leaved pulp, the main producing countries have continuously reduced their shipments to China, and there is a shortage of essential demand during the downstream peak season. Port inventory is at a relatively low level compared to the same period. The structural rebound of broad-leaved pulp continues, and the market expects the next round of quotations to break through the $600 line. The current price difference between coniferous and broad-leaved trees is low. Last week, the decline in coniferous trees caused broad-leaved trees to weaken, but they followed the market and returned to the upward trend after the week.
3. The peak season on the demand side is not prosperous, and the gross profit of finished paper is weak
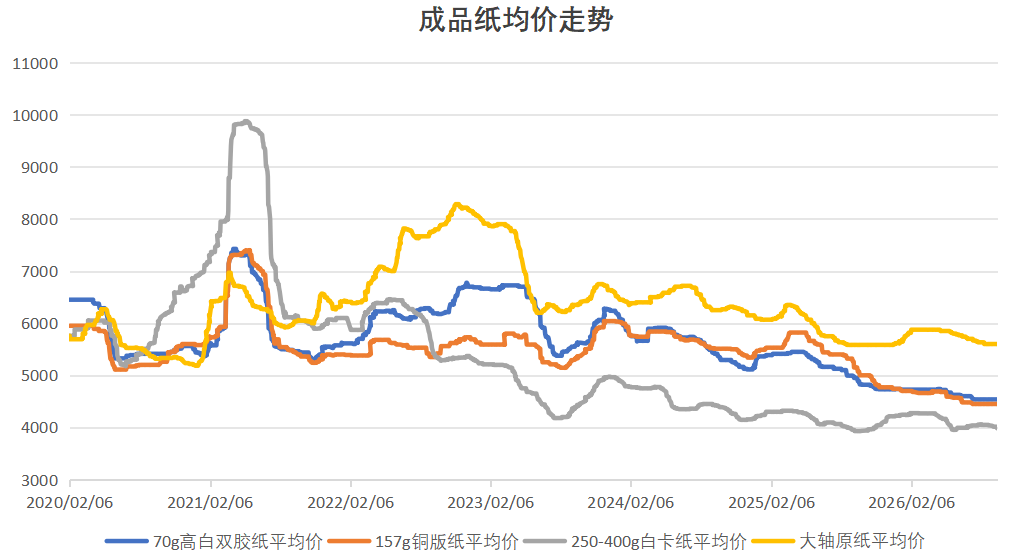
Paper mills continue to focus on destocking, with production and sales of mainstream paper varieties at historically low levels. Finished paper prices continue to decline, and there is significant pressure on shipments. The paper mill mainly focuses on reducing prices and increasing production volume, and it is difficult to increase the short-term operating rate. Therefore, it is cautious to pursue high demand procurement of raw materials. Based on the worsening losses, several paper mills such as Jinguang are planning to raise the price of white cardboard by 200 yuan/ton by the end of the month, and are paying attention to the implementation situation.
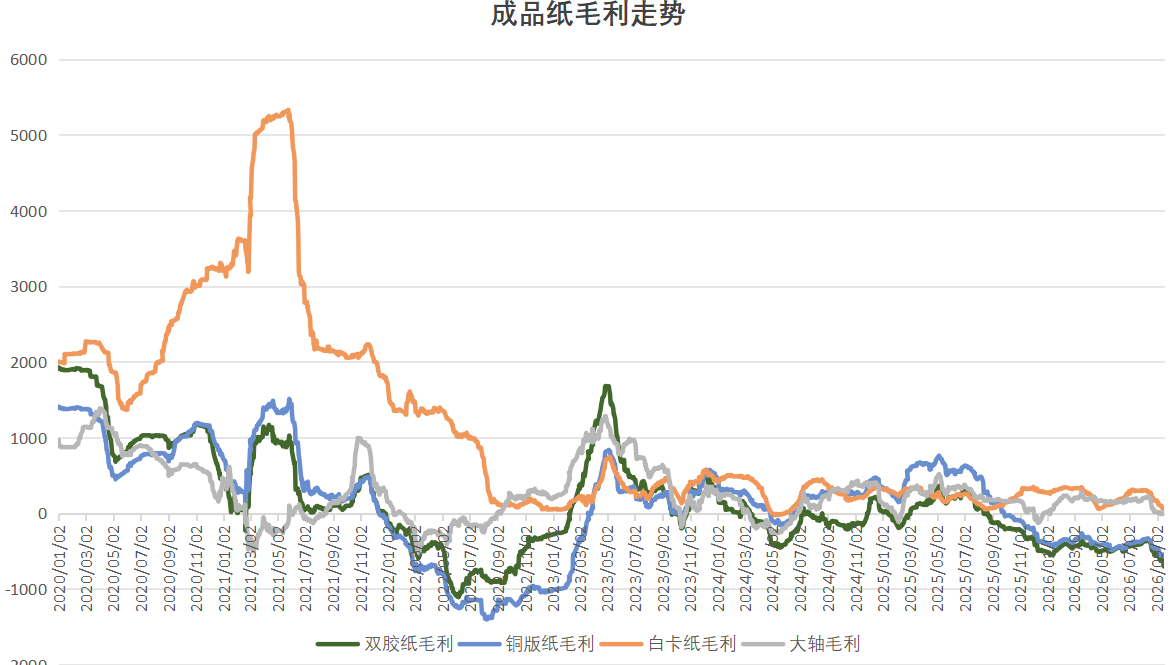
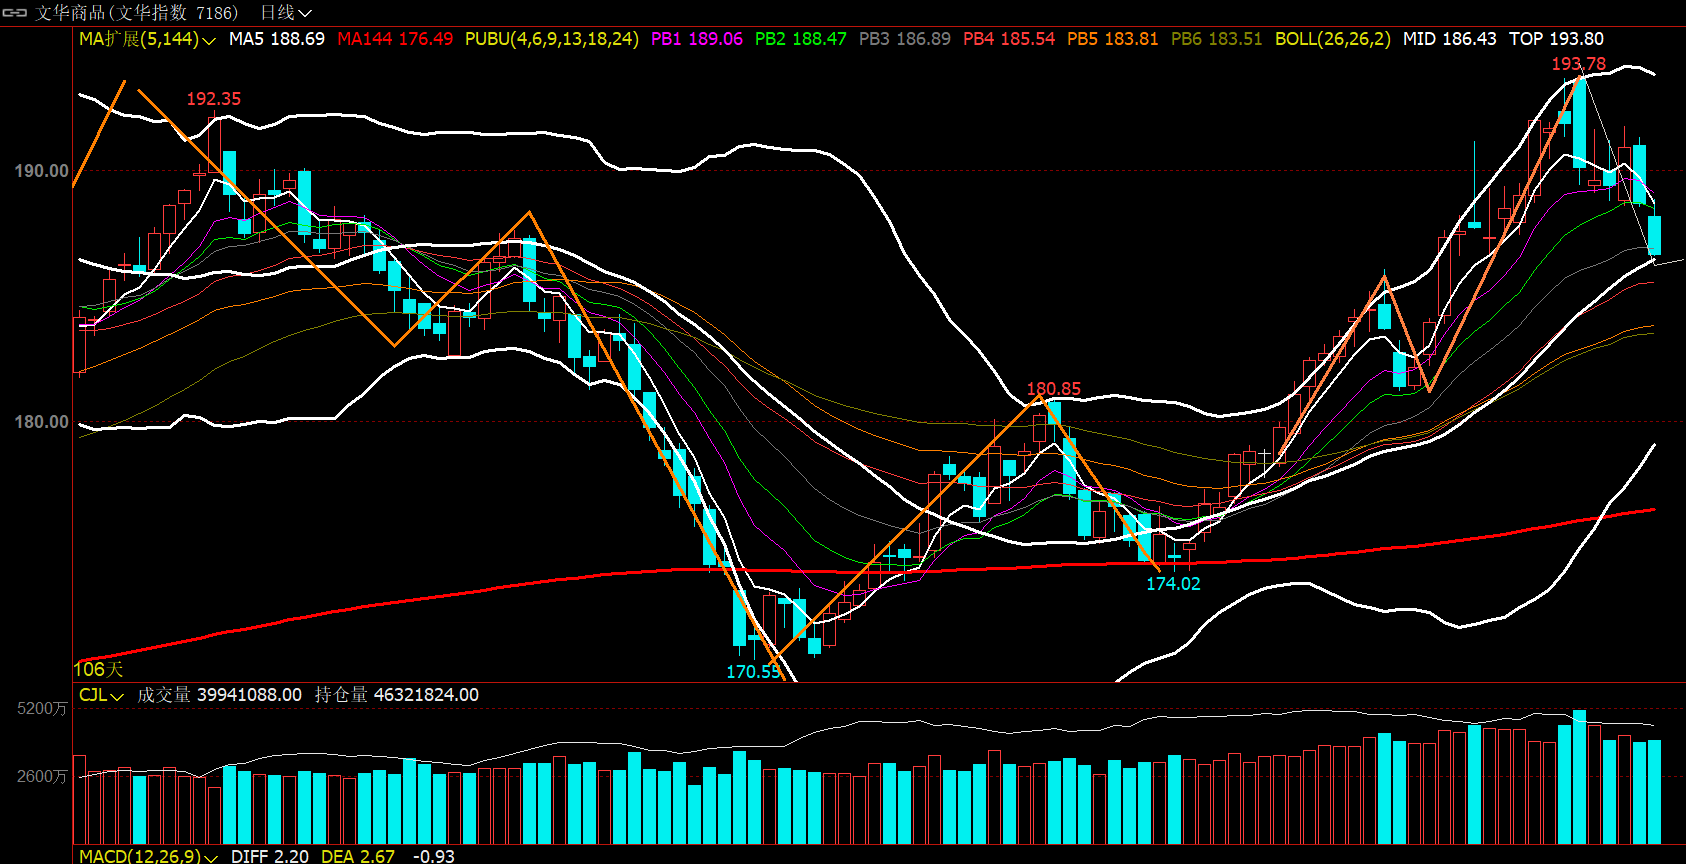
Overall, the production capacity of coniferous trees is still in the process of clearing, with strong support from cash flow costs in the vicinity of the first tier low of 4500. However, the high inventory in the port suppresses the space above, and there is significant hedging pressure near the import cost. The main core fluctuation range is still between 4600-4900, and the interval approach should be taken. However, based on the improvement of the supply and demand margin, the bearish trend of the long-term moving average system has turned volatile, and the medium to long term strategy is mainly focused on pullbacks and long positions. In terms of broadleaf, the available resources at the port are relatively tight, and there is support for peak season demand. The structural rebound continues, and we are concerned about the pressure on the $600 front line.
-
【Wdoodoo Weekly Paper Industry Report】The pulp warehouse receipt has been out of stock for a long time, and the packaging paper mill has raised prices in a centralized manner6981
-
【Wdoodoo Weekly Cotton Report】Multiple bearish factors converge, focusing on the support of seed cotton procurement costs8878
-
【Wdoodoo Weekly Cotton Report】Drought in U.S. cotton continues to intensify, with domestic demand closely monitored7865
-
【Wdoodoo Weekly Paper Industry Report】Pulp mills cut production to support pulp prices, while weak paper prices limit the upside5430
-
【Wdoodoo Weekly Cotton Report】Cotton: Drought fermentation in main production areas drives up cotton prices, while weak demand restricts space above7429