【Wdoodoo Weekly Cotton Report】Multiple bearish factors converge, focusing on the support of seed cotton procurement costs
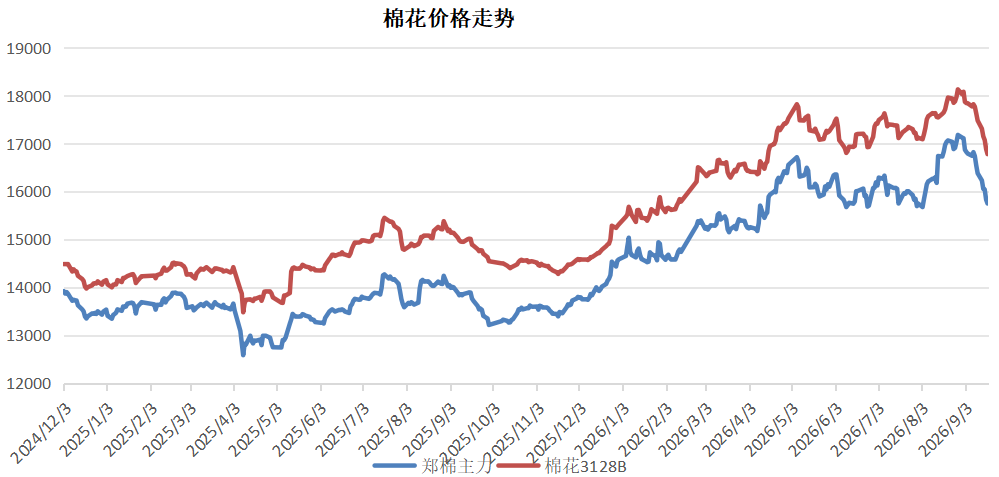
This week, both domestic and international cotton markets experienced overall downward pressure. CF01 closed at 15,750 yuan/ton, down 630 yuan/ton month-on-month; national cotton 3128B closed at 16,780 yuan/ton, down 700 yuan/ton month-on-month. The Fed's interest rate hike triggered a global risk-off sentiment, while the continued release of reserve cotton suppressed spot prices. Weak demand fulfillment during the downstream textile peak season led to synchronized corrections in both futures and spot markets.
1. Release of Macro-Level Negative Factors
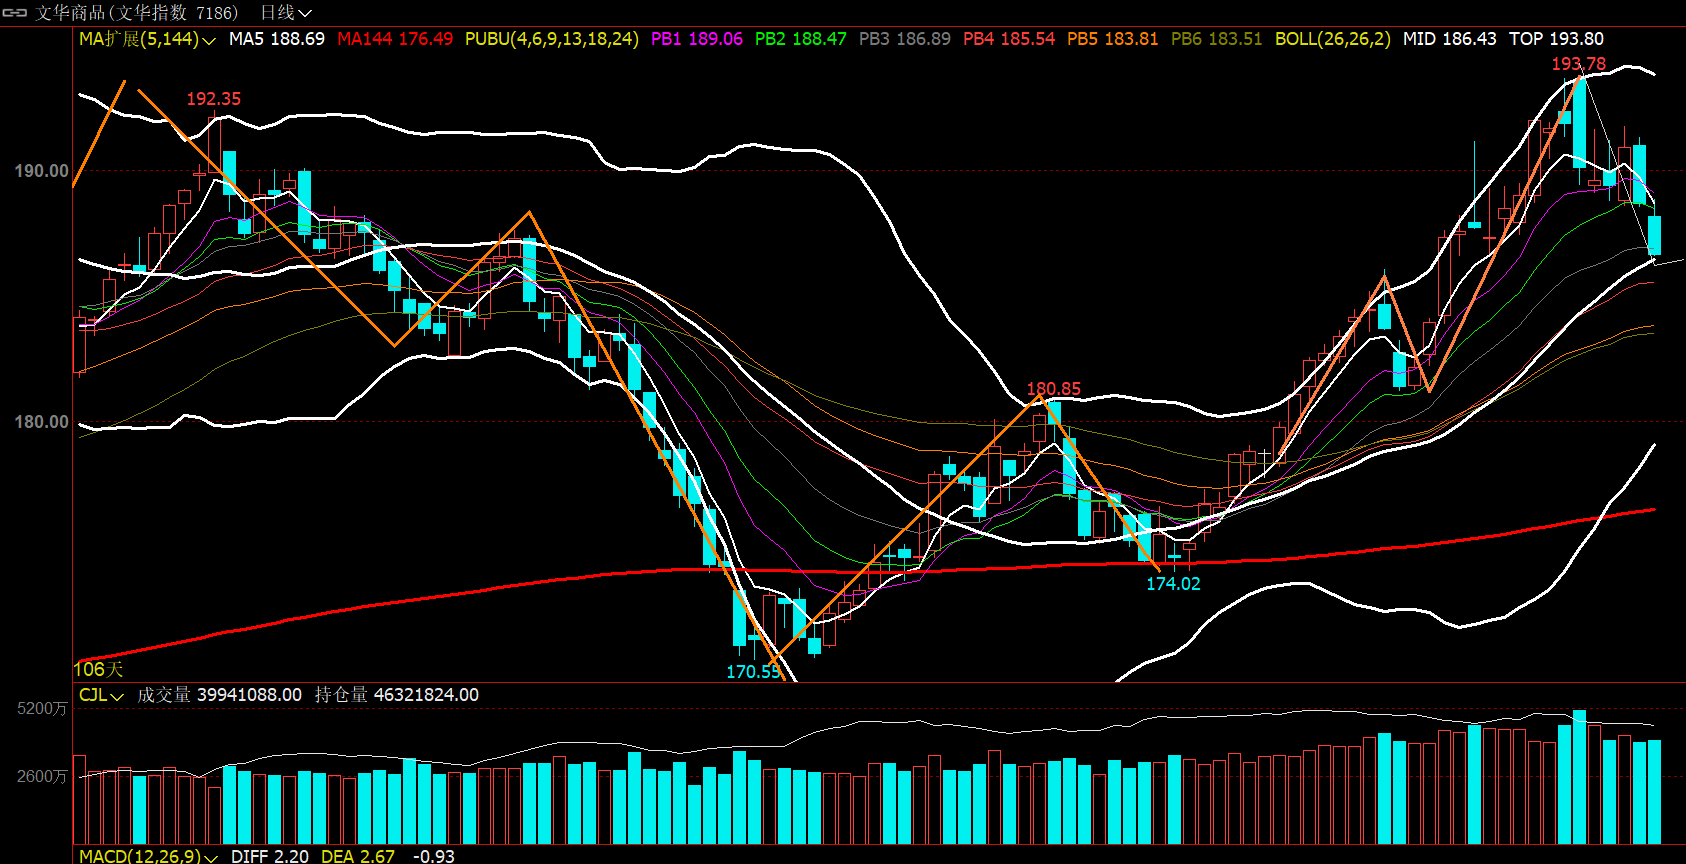
At the macro level, the overall sentiment is bearish. The Federal Reserve raised interest rates by 25 basis points as expected, intensifying expectations of tighter global liquidity and dampening the overall mood for commodities. Domestic retail sales data fell short of expectations, with insufficient boost in terminal consumption. However, short-term macroeconomic headwinds have already materialized, while recent intensive consultations between China and the U.S. have mitigated risks, limiting the impact of short-term macro shocks.
2、 Short term loose cotton supply suppresses upward potential.
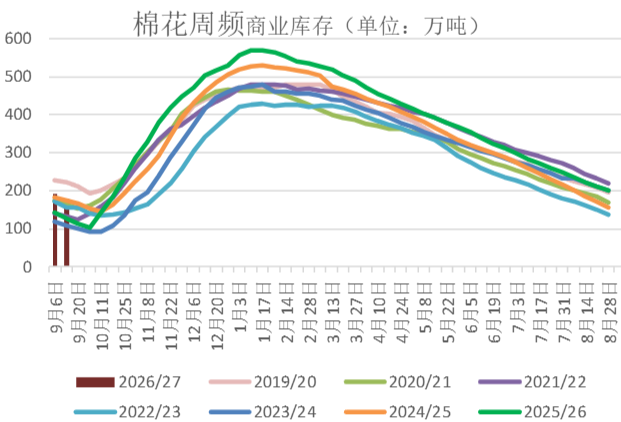
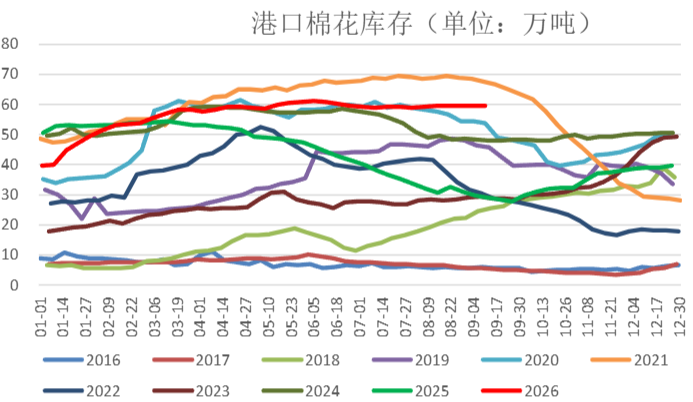
Domestic reserve cotton continues to be released, with unsold stocks occurring within the week. The bottom selling price of reserve cotton is 17014 yuan/ton (equivalent to standard grade 3128B), a decrease of 289 yuan/ton from last week, which has significantly suppressed spot prices. Combined with a significant increase in imports of cotton and cotton yarn during the year, port cotton inventories are at a high level, and the overall market supply is abundant.
In addition, most parts of Xinjiang have entered the peak of flocking, and cotton mills are preparing for weighing. It is expected that large-scale harvesting will begin in late September, and the supply pressure in October will be more fully released. The expected central cost for machine harvested seed cotton weighing is approximately 7.2-7.5 yuan/kg, corresponding to a comprehensive cost of approximately 16600-17400 yuan/ton for cotton skin.
3、 Lack of incremental demand in the market
The recovery of downstream textile demand is weak, and the peak season effect is generally realized. This week, the start-up load of textile enterprises fluctuated at a low level, but terminal orders were mainly short and small orders, lacking support from long orders. The inventory of finished products in the textile factory continues to accumulate, and the pace of destocking is slow. However, the inventory of all cotton greige fabric continues to be depleted at a low level, and high-quality aged cotton resources are scarce. The low price of cotton stimulates some low inventory textile enterprises to replenish their inventory, forming a temporary bottom support. Overall, the industry's demand remains in a state of rigid demand, and the lack of incremental demand is the core factor restricting the rebound of cotton prices.
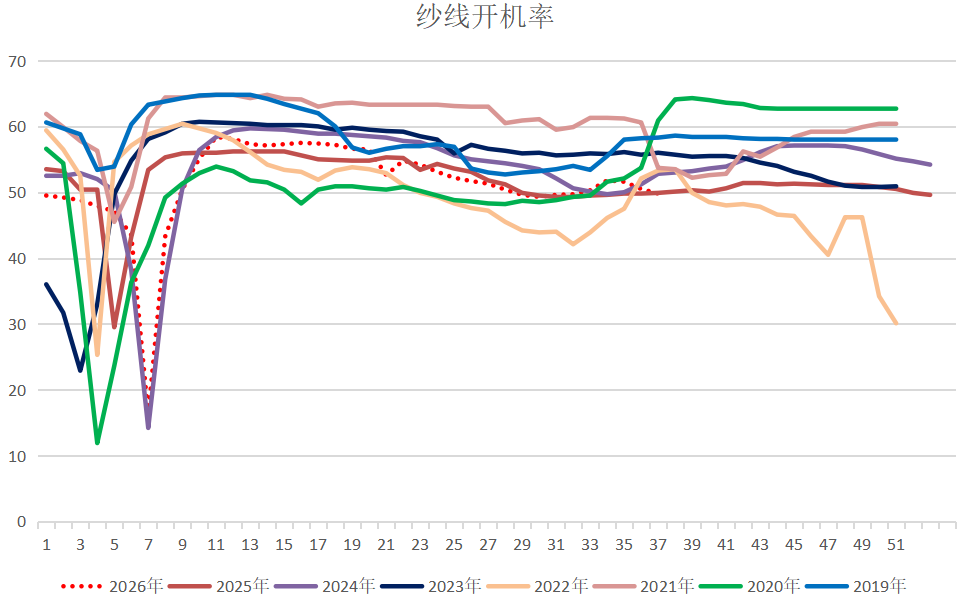
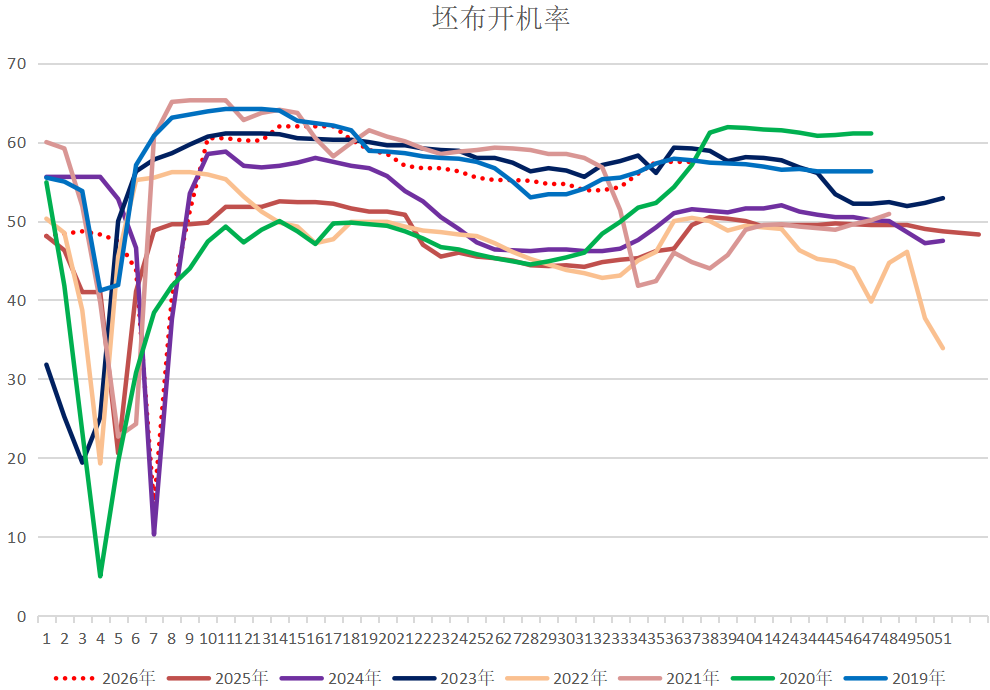
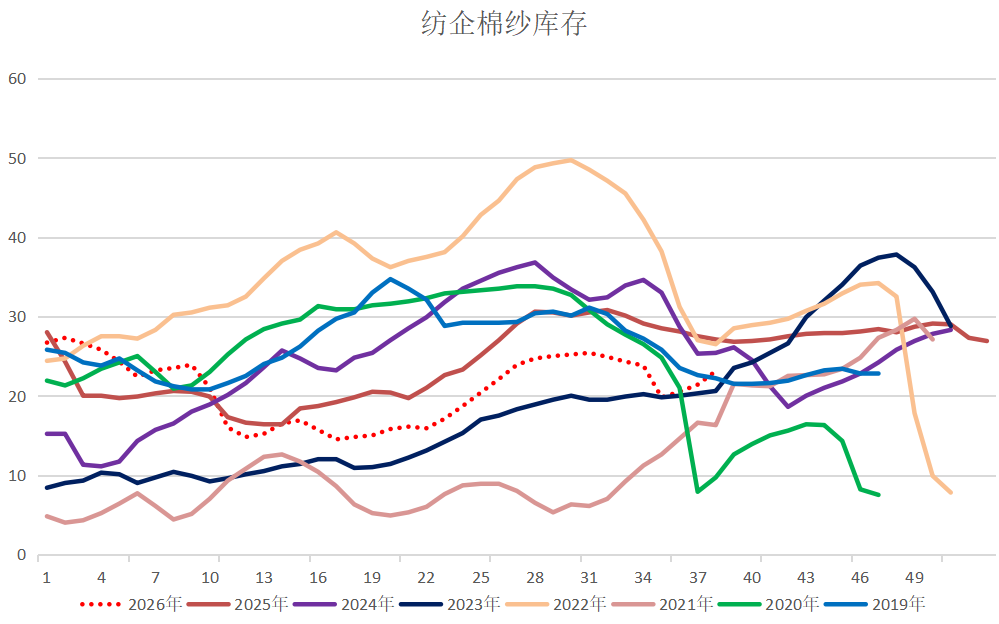
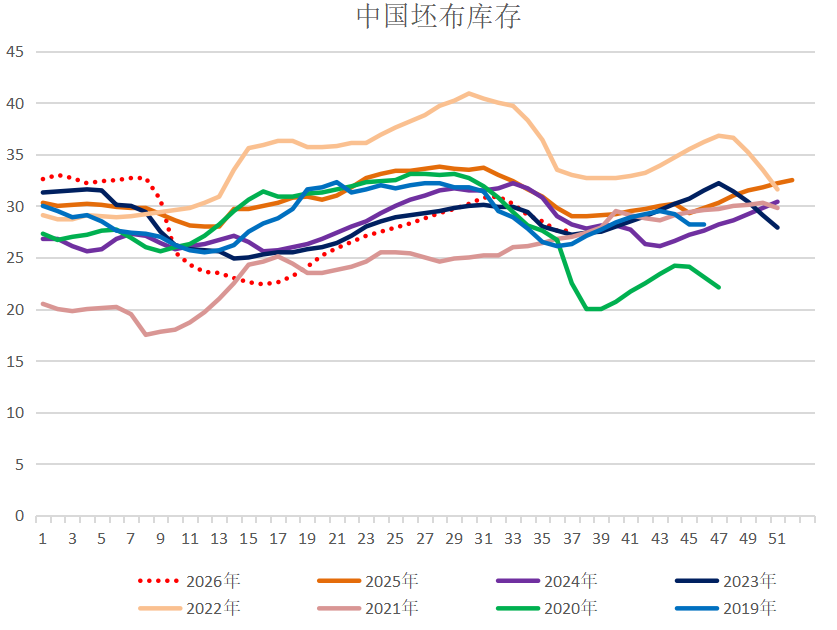
Overall, short-term macro bearish sentiment has been exhausted, and there is room for recovery after the market oversold. However, the fundamentals of industries with loose supply and weak demand have not substantially improved, and the rebound of cotton prices is highly restricted.
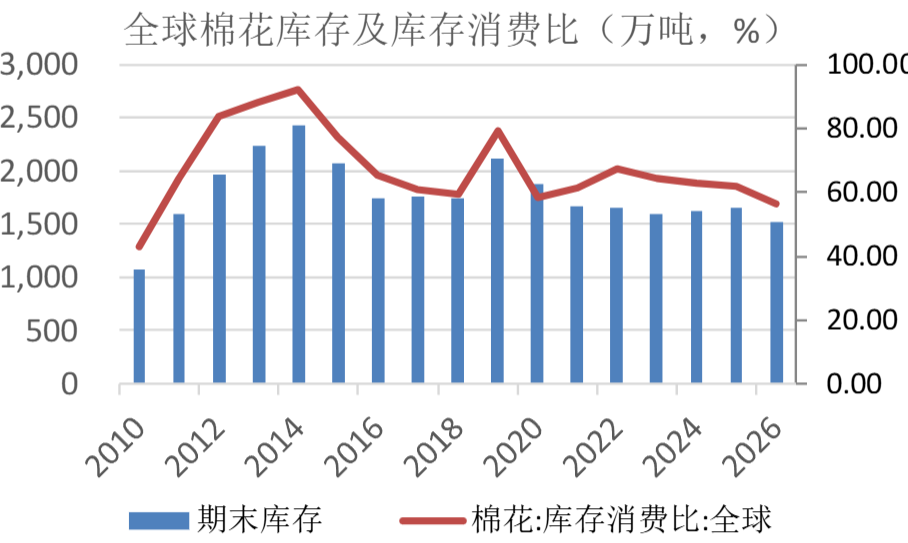
In the medium to long term, the global cotton production in the new year has fallen, the inventory consumption ratio is low, and the long-term supply and demand pattern is improving, providing bottom support for cotton prices. Coupled with the current cotton prices being close to the industry cost range, the downward space is relatively limited.
Maintain a neutral wait-and-see approach in operation and cautiously pursue short positions. Observe and wait for the purchase price of new cotton and the clear direction of downstream orders, or build a small amount of inventory at a low price. Follow up will focus on tracking the progress of Xinjiang's new cotton weighing, the increase in orders during peak season, and overseas monetary policy trends.
-
【Wdoodoo Weekly Paper Industry Report】The pulp warehouse receipt has been out of stock for a long time, and the packaging paper mill has raised prices in a centralized manner6981
-
【Wdoodoo Weekly Cotton Report】Multiple bearish factors converge, focusing on the support of seed cotton procurement costs8878
-
【Wdoodoo Weekly Cotton Report】Drought in U.S. cotton continues to intensify, with domestic demand closely monitored7865
-
【Wdoodoo Weekly Paper Industry Report】Pulp mills cut production to support pulp prices, while weak paper prices limit the upside5430
-
【Wdoodoo Weekly Cotton Report】Cotton: Drought fermentation in main production areas drives up cotton prices, while weak demand restricts space above7429