【Wdoodoo Weekly Pulp Report】Beneath the bearish consolidation, bulls are quietly building positions.
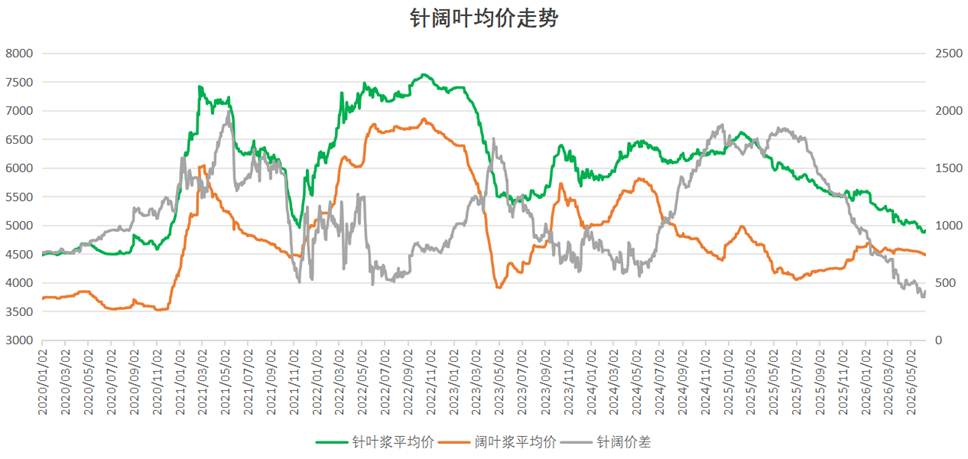
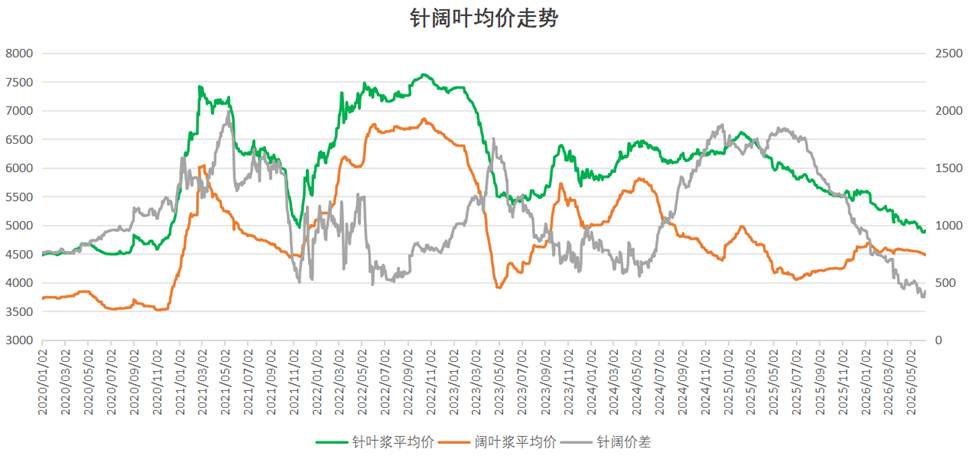
Pulp stayed in low-range consolidation this week. Driven by oversold rebound on futures market, the average price of softwood pulp stood at around RMB 4,905/ton, up RMB 30 week-on-week; hardwood pulp edged down slowly with spot average price at RMB 4,480/ton, a weekly drop of RMB 18. Downstream end demand offers limited support amid off-season. Paper mills keep cutting prices to destock and show little willingness to restock raw materials, leaving trading activity sluggish across the market.
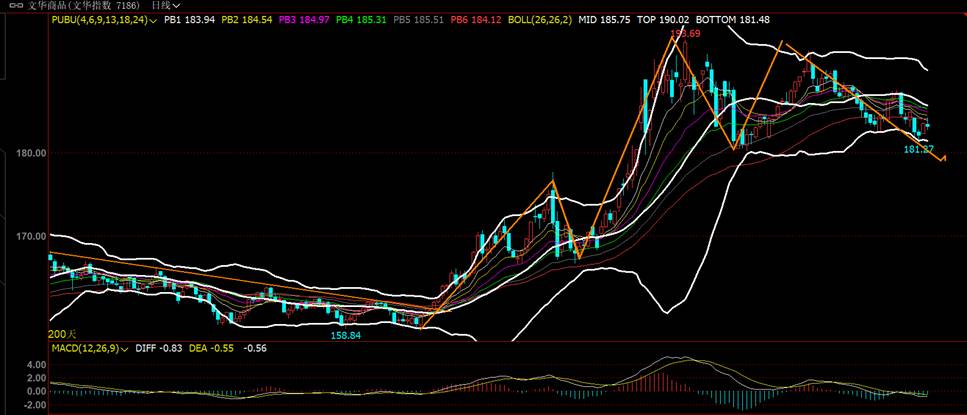
1. Mounting Global Liquidity Tightening Expectations; Bearish Macro Pressure Weighs on Commodities
2. Heavy Inventory Burden; Overseas Offer Prices Soften
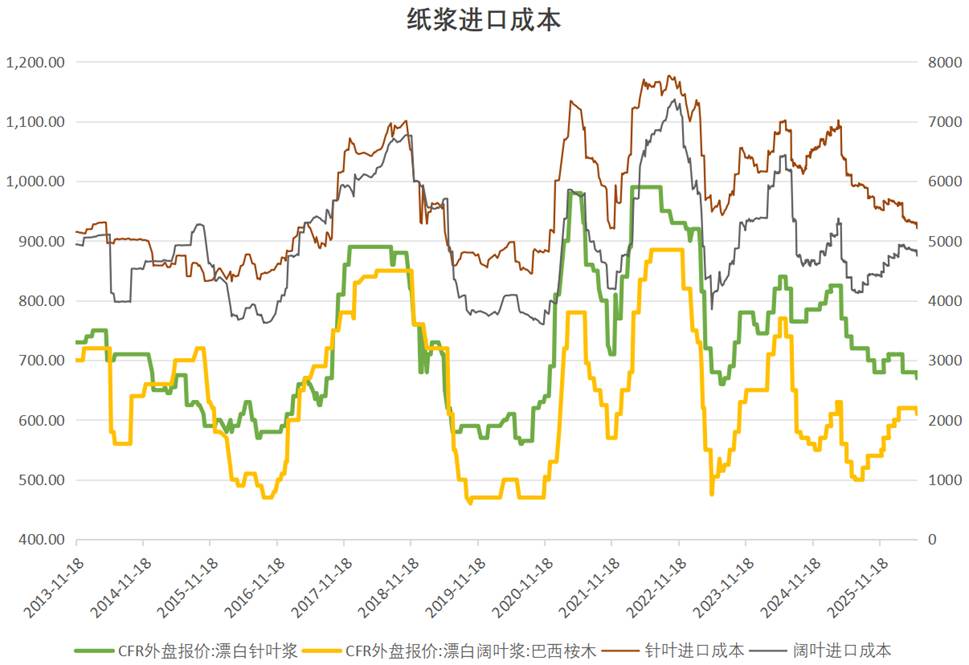
Actual overseas softwood pulp transactions weakened in this round amid cautious downstream purchasing. Chilean Arauco released monthly nominal offers: Silver Star at USD 670/ton, down USD 10 from prior levels; Star unchanged at USD 610/ton; Golden Star USD 640/ton, up USD 10/ton.
Softwood pulp supply at ports remains ample. After last week’s oversold futures rebound, some spot traders held back sales at low prices, yet this failed to lift purchasing sentiment among paper mills.
Hardwood pulp faces milder inventory pressure, but softwood-hardwood price spread stays low. Sliding softwood prices plus weakened rigid downstream demand in off-season drag down hardwood pulp performance. Reports indicate most actual overseas softwood and hardwood transaction prices slipped, with only a few brands holding firm offers.
3. Paper Mills Prioritize Price Cuts for Destocking; Raw Material Restocking Sentiment Weak
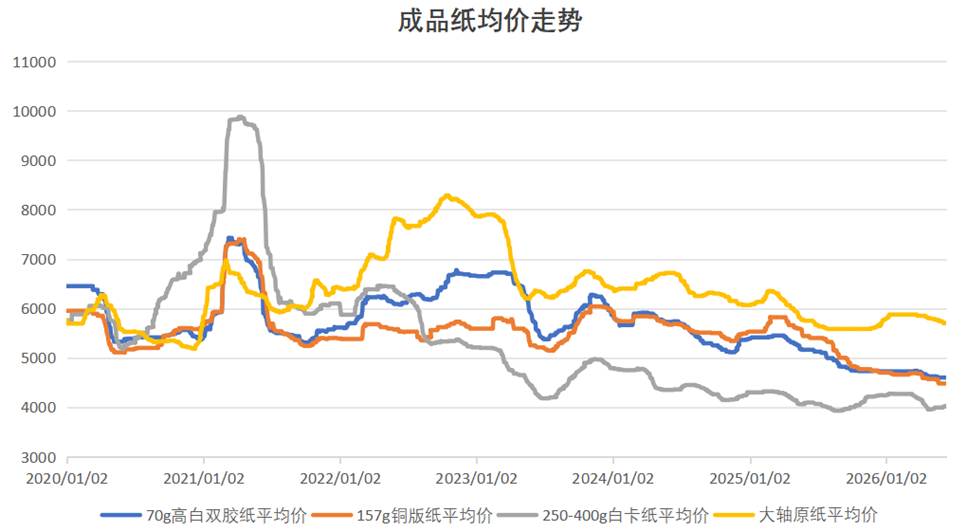
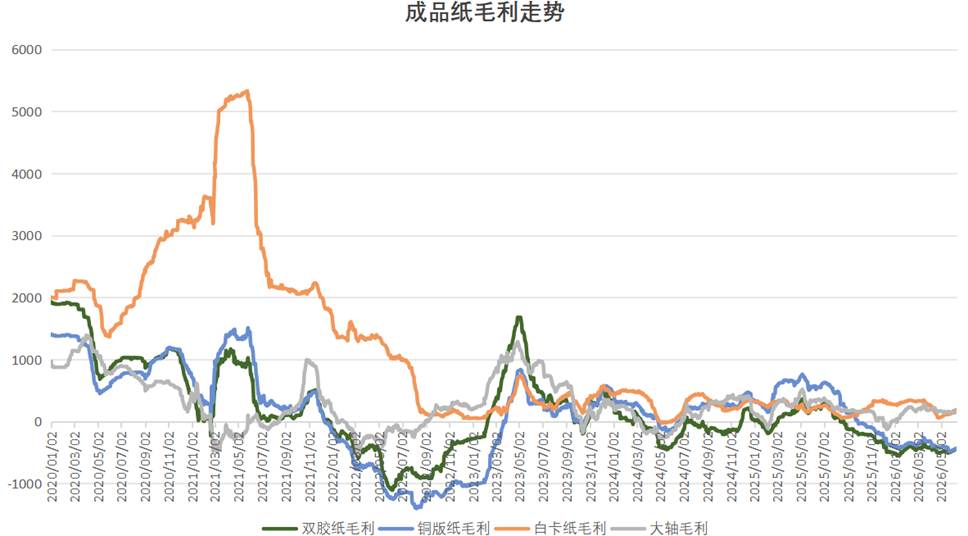
Off-season conditions persist with sluggish terminal orders. Paper mills are under prominent destocking pressure and continue to rely on price cuts to clear inventories, while downstream processors remain reluctant to replenish finished goods and raw material stocks. Except for white cardboard, operating rates of all major paper grades declined month-on-month. Double-coated paper, offset paper and household paper operating rates fell by 1.53%, 1.15% and 1.52% respectively, pointing to sustained weakness in end demand.
4. High Inventories Cap Price Upside
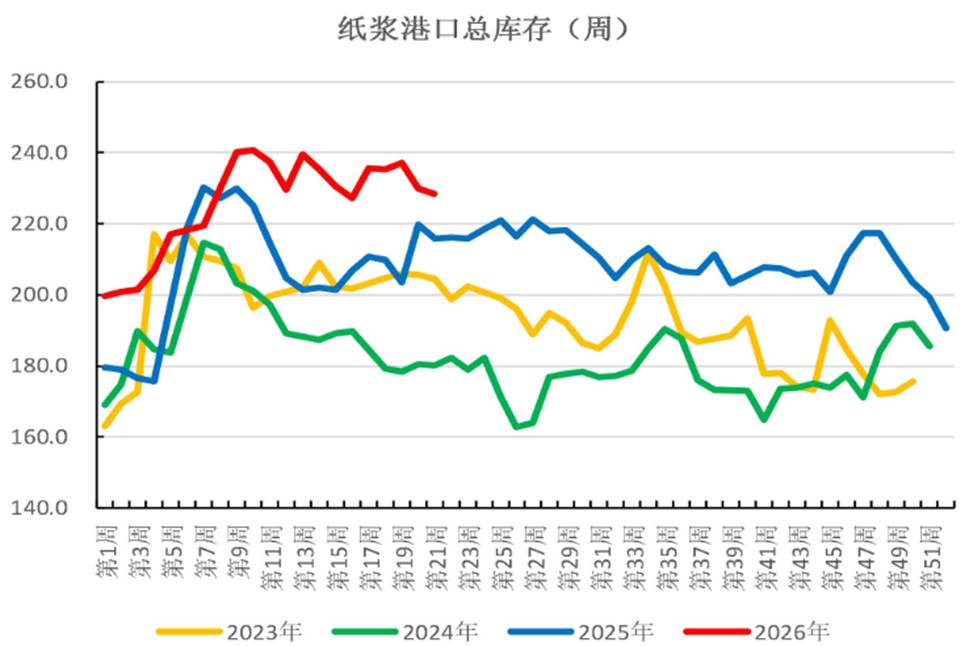
As of June 11, monitored inventory at major ports reached 2.33 million tons, rising 40,000 tons month-on-month and staying at a multi-year seasonal high. The high proportion of softwood pulp keeps weighing on pulp prices.
Comprehensive Outlook,Bearish macro sentiment, elevated port inventories, lower overseas offers, widespread price-cut destocking by paper mills and weak raw material restocking willingness jointly create a quiet trading market.
-
【Wdoodoo Weekly Cotton Report】Raw paper processing is under pressure, and the pulp trend is loose9797
-
【Wdoodoo Weekly Cotton Report】New cotton arrivals support prices, while weak demand hampers rebound7500
-
【Wdoodoo Weekly Paper Industry Report】Port destocking slows down, pulp surges fail6432
-
【Wdoodoo Weekly Cotton Report】Supply and demand margins slightly improve, seed cotton stabilizes to support cotton prices5237
-
【Wdoodoo Weekly Paper Industry Report】The pulp warehouse receipt has been out of stock for a long time, and the packaging paper mill has raised prices in a centralized manner7136