【Wdoodoo Weekly Cotton Report】Domestic & Foreign Cotton: Trading New Crop Planting; Zhengzhou Cotton Extends Gains Amid Rollover
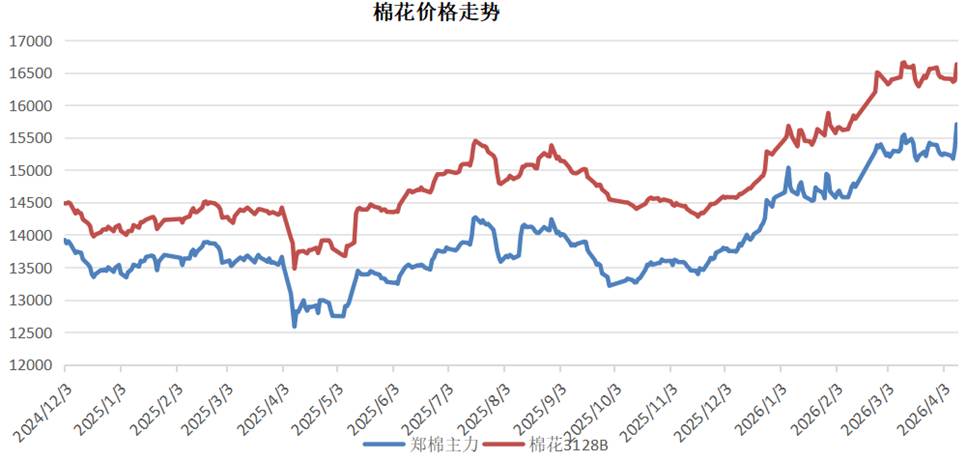
Last week, Zhengzhou cotton edged lower before rebounding and completed the major contract rollover. CF09 closed at 15,705 yuan/ton, up 309 yuan/ton from the previous week, while Cotton 3128B closed at 16,630 yuan/ton, up 220 yuan/ton. Speculation over production cuts during the planting season has been the main theme in April.
1.The Middle East situation is unlikely to see a substantive resolution in the short term.
Last week, the US and Iran reached a tentative truce, but weekend peace talks ended without progress. President Trump stated that the United States would impose a blockade on the Strait of Hormuz, noting that what could not be secured on the battlefield will be even harder to achieve at the negotiating table. With the US accelerating military deployments, the US-Israel-Iran conflict faces risks of escalating beyond expectations.
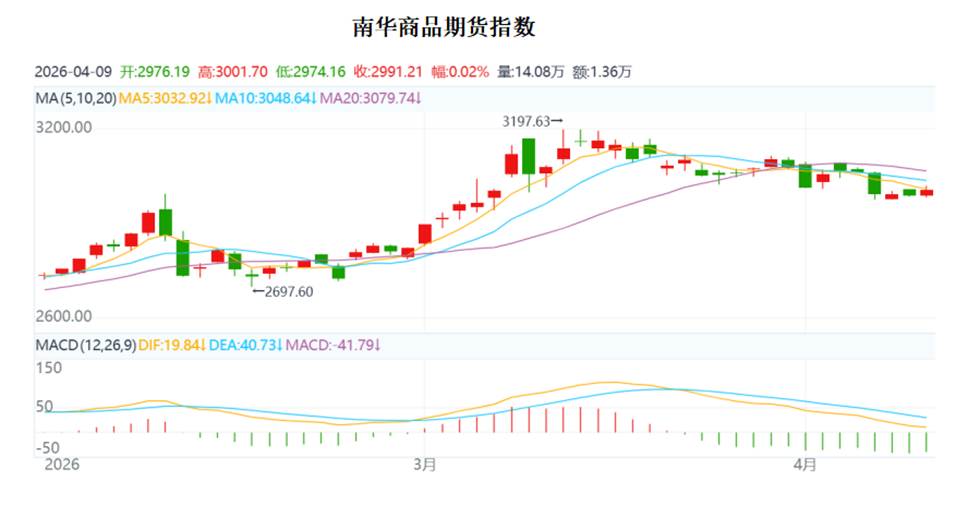
As the Middle East remains mired in a cycle of simultaneous fighting and negotiations, the situation is evolving toward prolonged confrontation with periodic escalations in intensity, which will continue to impact crude oil production and shipping in the Persian Gulf. Due to the repricing of war risk insurance and the lag in restoring shipping order, commodity costs are expected to remain elevated for an extended period. However, forward-dated contracts may begin pricing in a recessionary narrative, warranting vigilance toward shifts in the futures term structure.
2. Expectations of reduced new-crop planting are the main focus of the current market.
3. Demand support remains, but marginal weakening is expected.
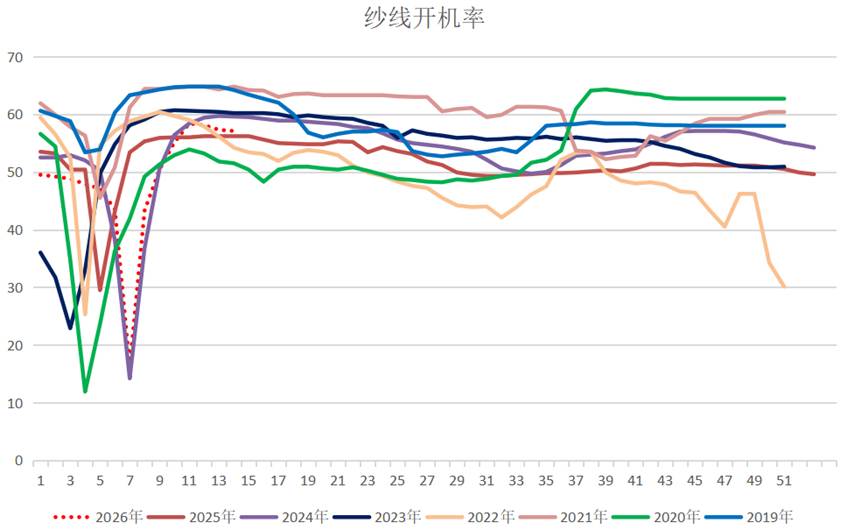
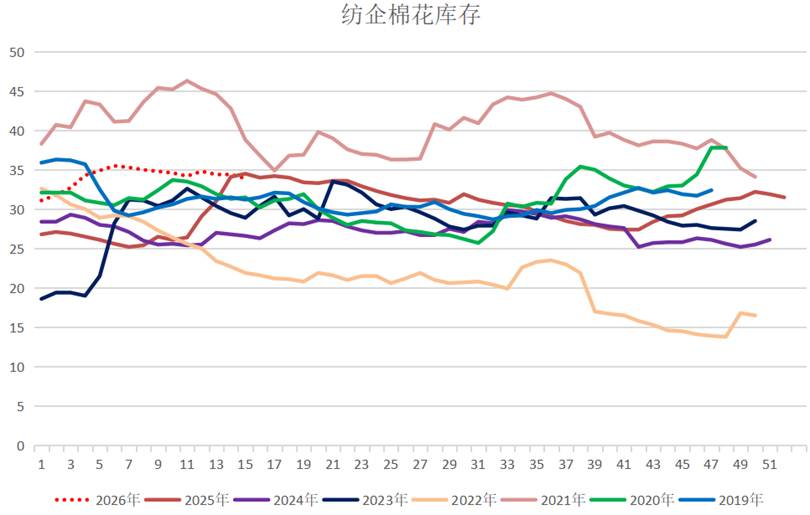
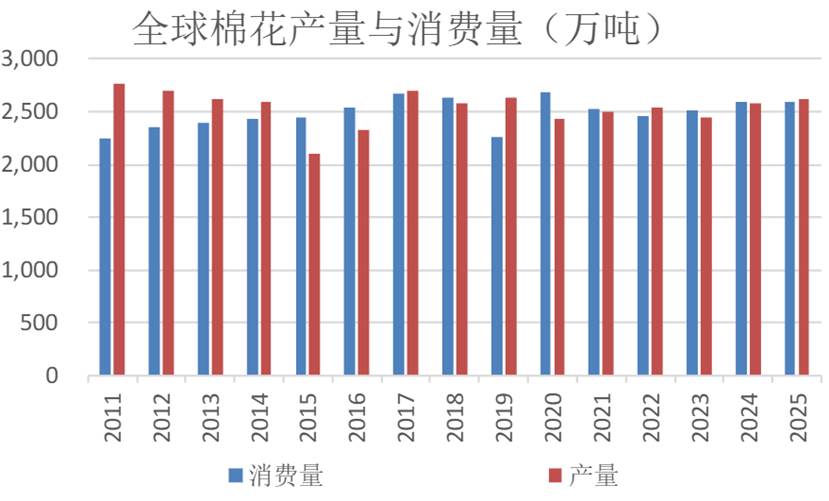
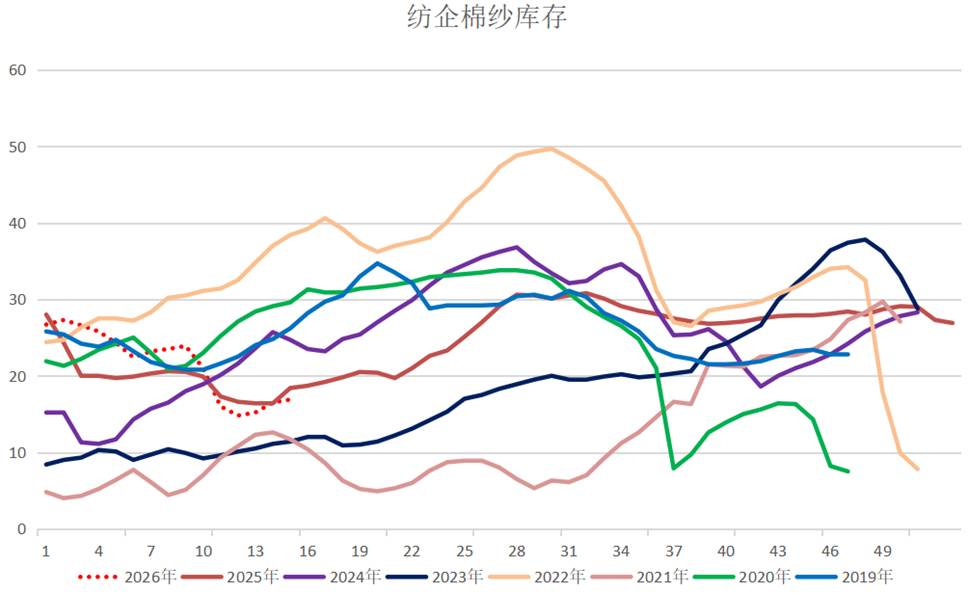
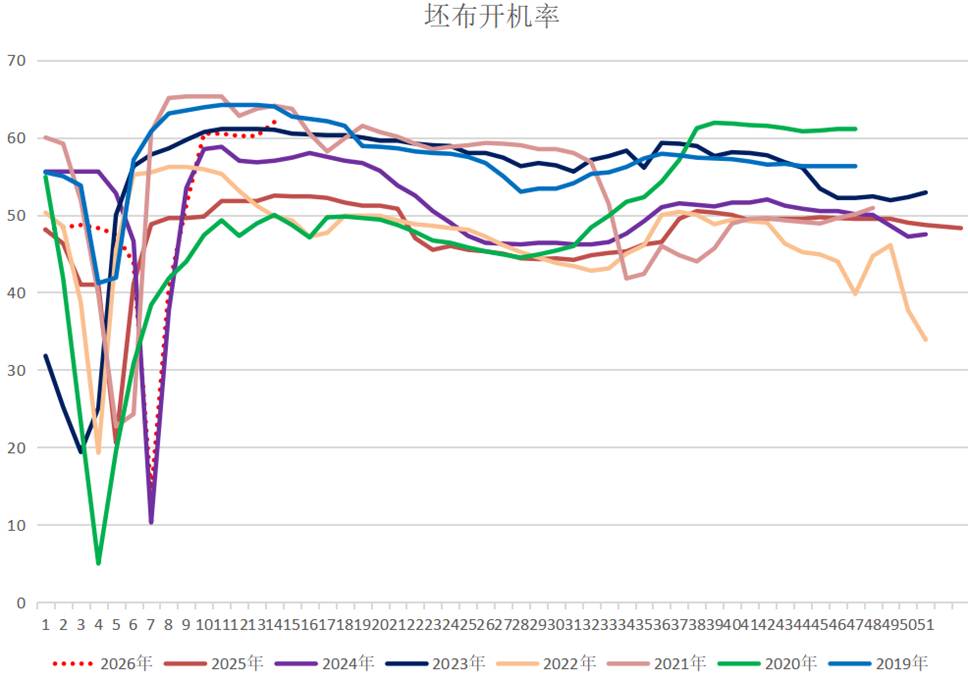
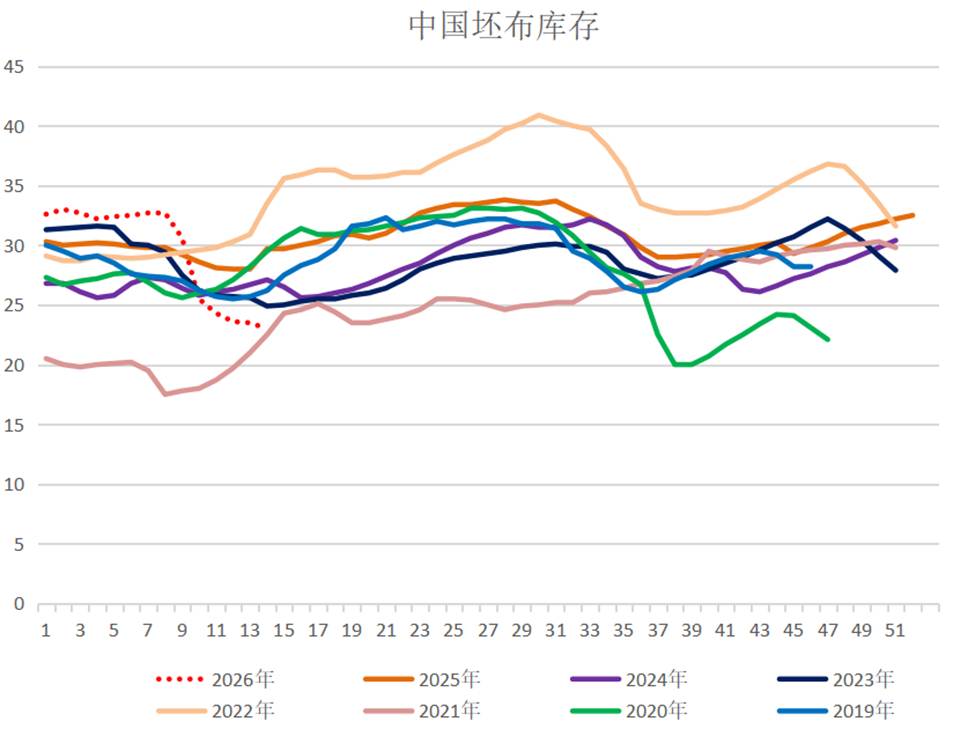
Textile mill operating rates slightly declined, raw material inventories decreased month-on-month, and spinners' yarn inventories rose marginally month-on-month, although total inventory levels remain low. Grey fabric operating rates continued to rebound, and fabric mills' finished goods inventories continued to fall month-on-month. Spinners reported that orders and sales for 40-count yarn remain decent, while other varieties show signs of slowing. Demand in April is expected to weaken marginally, leading to cautious restocking among textile enterprises. Despite robust cotton consumption amid high capacity, the demand side is more of a support factor rather than a driver given expectations of downstream weakness.
Key Focus This Week
The persistence of geopolitical conflicts in the Middle East.
Policies regarding Xinjiang cotton planting area for the new season.
Performance of end-demand.
-
【Wdoodoo Weekly Cotton Report】Raw paper processing is under pressure, and the pulp trend is loose9797
-
【Wdoodoo Weekly Cotton Report】New cotton arrivals support prices, while weak demand hampers rebound7500
-
【Wdoodoo Weekly Paper Industry Report】Port destocking slows down, pulp surges fail6432
-
【Wdoodoo Weekly Cotton Report】Supply and demand margins slightly improve, seed cotton stabilizes to support cotton prices5237
-
【Wdoodoo Weekly Paper Industry Report】The pulp warehouse receipt has been out of stock for a long time, and the packaging paper mill has raised prices in a centralized manner7136